What Is a Summary of Benefits and Coverage? Key Facts
The Summary of Benefits and Coverage is a standardized document that helps you compare health plans and avoid surprise bills. Learn how to read it effectively.
By Jocelyn Fairmont
Compare health plans
Finding plans in your area…
Your health insurance policy comes with a stack of paperwork, but one document stands out as the most practical tool for understanding what you are actually buying. The Summary of Benefits and Coverage, often called the SBC, is a standardized document that every health plan must provide. It exists to cut through confusing policy language and give you a clear, side-by-side comparison of what a plan covers, what it costs, and how it works. If you have ever felt overwhelmed by deductibles, copays, and network rules, the SBC is your starting point for making an informed decision.
The SBC was created under the Affordable Care Act to bring transparency to the health insurance market. Before this requirement, plans could bury critical details in lengthy contracts, making it nearly impossible for the average person to compare options. Today, every plan sold on the ACA Marketplace, and most job-based plans, must give you an SBC that follows a strict template. This means you can look at two different plans and quickly see how they stack up against each other. Understanding this document is a core skill for anyone shopping for coverage, whether you are enrolling through the Marketplace or evaluating a job offer.
What Exactly Is a Summary of Benefits and Coverage?
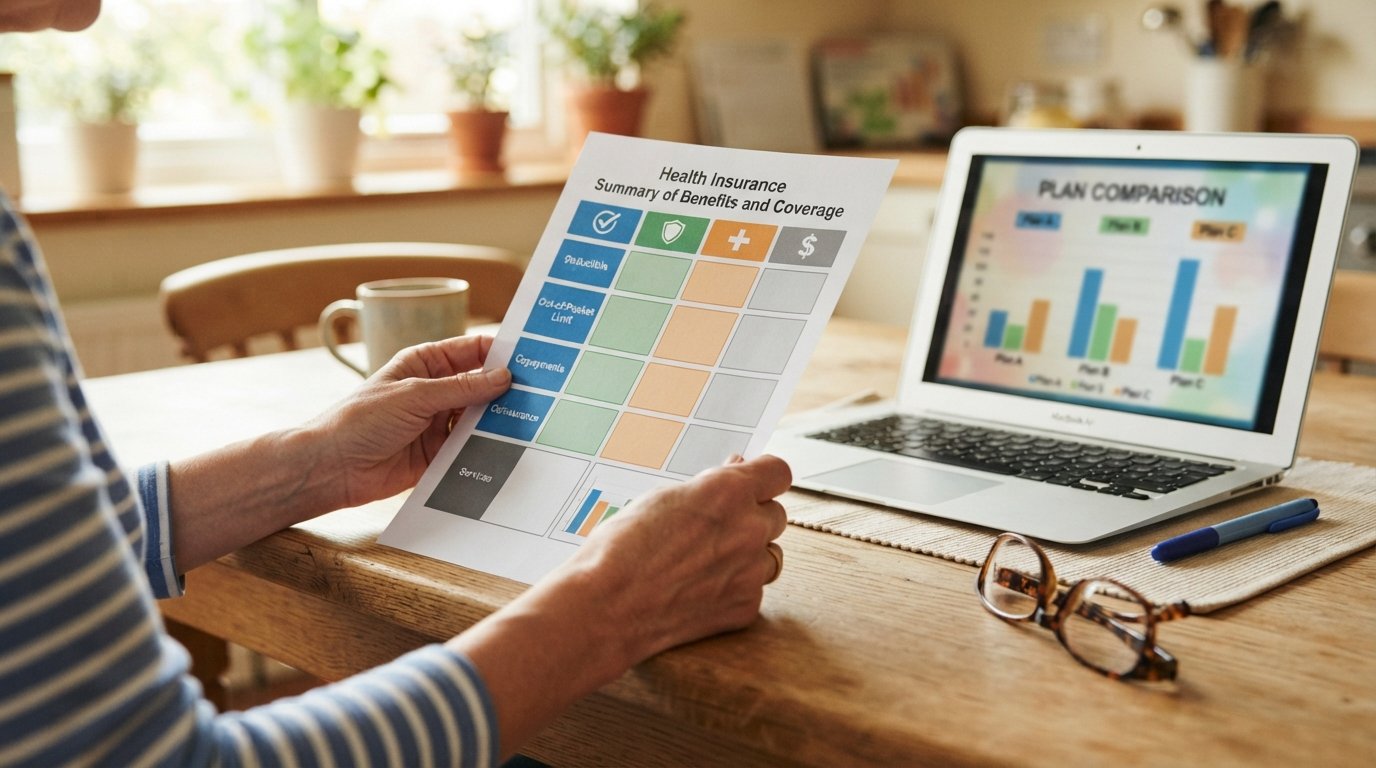
The Summary of Benefits and Coverage is a concise, plain-language document that summarizes the key features of a health insurance plan. It is not the full policy contract, but rather a snapshot designed to answer the most common questions people have when choosing coverage. The SBC must be provided to you before you enroll, and you can request a copy at any time from your insurer or employer. It is typically four to eight pages long and uses a consistent format across all plans, so you can compare them easily.
The document covers several essential areas. First, it outlines the general plan information, such as the type of plan (HMO, PPO, EPO, or POS), who is eligible, and what network you must use. Second, it provides a detailed breakdown of costs, including deductibles, copays, coinsurance, and out-of-pocket limits. Third, it includes a coverage table that shows how much you pay for common services like primary care visits, specialist visits, emergency room care, and prescription drugs. Finally, it includes a glossary of terms and a coverage examples section that illustrates how much you might pay in real-life scenarios.
One of the most valuable parts of the SBC is the coverage examples. These examples show costs for two common situations: having a baby and managing type 2 diabetes. Each example walks through a series of services and shows what the plan would pay and what you would pay. This real-world illustration helps you understand the financial impact of a plan beyond just the monthly premium. For instance, a plan with a low premium might have a high deductible, meaning you could pay thousands out of pocket before coverage kicks in. The examples make these differences tangible.
Why the SBC Matters When Choosing a Health Plan
Health insurance is one of the most significant purchases you will make, yet many people select a plan based solely on the premium. The SBC forces you to look beyond the monthly cost and consider the total picture. A plan with a cheap premium might seem attractive, but if it has a $10,000 deductible and limited coverage, you could face overwhelming bills if you get sick. Conversely, a higher premium plan might offer lower deductibles and better coverage, saving you money in the long run. The SBC helps you weigh these trade-offs.
When you compare SBCs side by side, you can see exactly how much you would pay for a doctor visit, a hospital stay, or a prescription. This is especially important if you have ongoing medical needs. For example, if you take an expensive medication, you need to know how the plan covers prescription drugs. The SBC includes a section on prescription drug coverage that indicates whether you pay a flat copay or a percentage of the cost (coinsurance). It also tells you if you need prior authorization or step therapy, which can affect your access to medications. Understanding these details can prevent surprise bills and delays in care.
Another reason the SBC is crucial is that it standardizes information. Insurance companies cannot hide behind jargon or bury key limitations. The format requires them to disclose whether a plan covers certain benefits, such as mental health services, maternity care, and preventive care. You can quickly see if a plan excludes a service you need. This transparency empowers you to make a choice that aligns with your health and financial situation. If you are navigating the complexities of dual coverage, for example, you might need to coordinate benefits carefully; our guide on Dual Health Insurance Coverage: Rules, Benefits, and Pitfalls explains how to avoid gaps and maximize savings.
For those shopping on the ACA Marketplace, the SBC is even more critical because it helps you determine if you qualify for subsidies. The Marketplace uses the SBC to calculate the second-lowest-cost Silver plan, which determines your premium tax credit. By reviewing SBCs, you can estimate your total costs and choose a plan that fits your budget. Whether you are enrolling through NewHealthInsurance.com or another platform, always ask for the SBC before you commit.
How to Read and Compare SBCs Effectively
Reading an SBC might seem daunting at first, but it becomes straightforward once you know what to look for. Start by identifying the plan type and network. HMO plans require you to stay in-network and get referrals from a primary care doctor. PPO plans offer more flexibility but usually cost more. EPO plans have a network but no referrals. POS plans blend features of HMO and PPO. Knowing the plan type tells you how much freedom you have in choosing doctors and hospitals.
Next, focus on the cost-sharing sections. The deductible is the amount you pay before the plan starts covering most services. Look for separate deductibles for medical and prescription drugs. The out-of-pocket maximum is the most you will pay in a year for covered services; after you reach it, the plan pays 100% of covered costs. Copayments are fixed amounts you pay for services, like $30 for a primary care visit. Coinsurance is a percentage you pay, like 20% of the cost of a specialist visit. These numbers determine your financial responsibility.
When comparing plans, create a list of your expected medical needs for the year. Then, for each SBC, find the corresponding costs. Here is a simple checklist to guide your comparison:
- Monthly premium: The amount you pay each month for coverage.
- Deductible: How much you pay before coverage begins.
- Copays and coinsurance: Your share of costs for specific services.
- Out-of-pocket maximum: The cap on your annual spending.
- Prescription drug coverage: Which tiers, copays, and restrictions apply.
After listing these details, use the coverage examples in the SBC to see how the plan performs in real scenarios. The maternity and diabetes examples are standard, but you can apply the same logic to your own situation. For instance, if you have a chronic condition, estimate how many specialist visits and prescriptions you will need, then calculate your total costs under each plan. This exercise reveals which plan offers the best value for your specific needs.
Remember that the SBC is not the entire policy. It does not include every detail, such as specific exclusions or prior authorization requirements for every service. For those specifics, you should consult the plan's full benefits booklet or contact the insurer. However, the SBC gives you a solid foundation for comparison. If you are considering Medicare, resources like NewMedicare provide educational tools to help you understand Medicare Advantage, Medigap, and Part D plans, which also use SBCs to summarize coverage.
Key Sections of the SBC and What They Tell You
The SBC is organized into several sections, each serving a distinct purpose. The first section, "Important Questions," answers basic questions like "What is the overall deductible?" and "Are there other deductibles for specific services?" It also tells you if there are any services covered before you meet the deductible, such as preventive care. This section gives you a quick overview of the plan's cost structure.
The second section, "Common Medical Events," is a table listing services like primary care visits, specialist visits, emergency room care, and prescription drugs. For each service, it shows what you pay in-network and out-of-network (if applicable). This table is where you can compare how plans handle the services you use most. For example, one plan might charge a $20 copay for primary care, while another charges 20% coinsurance. If you visit the doctor frequently, the copay plan could save you money.
The third section, "Excluded Services and Other Covered Services," lists what the plan does not cover and what it covers but may require prior authorization. This is crucial for avoiding surprises. If a plan excludes a service you need, you would have to pay entirely out of pocket. The SBC also notes if there are limits on coverage, such as a maximum number of visits per year for therapy. Always check this section against your specific needs.
The fourth section, "Coverage Examples," provides the real-world scenarios mentioned earlier. It shows how much the plan would pay and how much you would pay for having a baby and managing type 2 diabetes. These examples assume you are in-network and use specific services. They help you understand the plan's financial impact beyond the premium. If the example shows you paying a large portion of the cost, you might want to look for a plan with better coverage.
The final section includes the glossary and a statement of your rights. The glossary defines terms like deductible, coinsurance, and prior authorization. It is a handy reference if you encounter unfamiliar language. The statement of rights explains that you have the right to receive the SBC and that it must be accurate. If you find errors, you can contact your insurer or the Department of Labor.
The SBC and Prior Authorization: What You Need to Know
The SBC does not provide a comprehensive list of every service that requires prior authorization, but it does indicate whether prior authorization is required for certain benefits. Prior authorization is a process where your doctor must get approval from the insurance company before a service, medication, or procedure is covered. If you skip this step, the plan may deny coverage, leaving you with a large bill. The SBC often notes that "prior authorization may be required" for specific services, such as certain prescriptions or imaging tests.
For example, the prescription drug section of the SBC might indicate that some medications require prior authorization or step therapy. Step therapy means you must try a less expensive drug first before the plan covers a more expensive one. If you currently take a medication that requires prior authorization, you should check the SBC to see if the plan covers it and what steps you need to take. This proactive approach can prevent delays in getting your medication.
In the common medical events table, the SBC may also note prior authorization requirements for services like MRI or CT scans. If you anticipate needing these services, you can plan ahead and work with your doctor to obtain authorization. Understanding these requirements is part of being an informed consumer. If you face a denial, you have the right to appeal. Many resources, including NewHealthInsurance.com, offer guidance on the appeals process and how to advocate for yourself.
It is also worth noting that the SBC is just one tool. For a deeper dive into prior authorization and how it affects your care, explore our articles on prior authorization basics and appeal rights. These resources can help you navigate the system and ensure you get the coverage you deserve.
Where to Get an SBC and How to Use It
You should receive an SBC from your insurance company or employer before you enroll in a plan. If you are shopping on the ACA Marketplace, the SBC is available for each plan you are considering. You can also request an SBC at any time from your insurer. If you are enrolled in a job-based plan, your employer must provide it to you automatically. If you cannot find it, contact your HR department or the insurance company directly.
Once you have the SBC, use it as a comparison tool. When evaluating multiple plans, lay the SBCs side by side and compare the costs for the services you expect to use. Do not just look at the premium; consider the deductible, copays, and out-of-pocket maximum. Also, check the network and whether your doctors and hospitals are included. If you have prescriptions, verify that they are on the plan's drug list and check the tier they fall under.
If you need help understanding an SBC or choosing a plan, NewHealthInsurance.com offers personalized assistance. Their licensed agents can walk you through the details and help you find a plan that fits your budget and health needs. You can call them at (833) 864-8035 for expert guidance. They work with major carriers like Humana, Cigna, Anthem, Kaiser Permanente, Aetna, and Ambetter Health, so you have access to a wide range of options.
Finally, remember that the SBC is a summary, not the full contract. If you have specific concerns, such as whether a particular treatment is covered, ask for the full policy documents. The SBC is your starting point for understanding a plan, but the details matter. By using the SBC effectively, you can avoid surprise bills and make confident decisions about your healthcare coverage.
The Summary of Benefits and Coverage is a powerful tool that levels the playing field between insurers and consumers. It gives you the information you need to compare plans apples-to-apples and choose coverage that protects your health and your wallet. Whether you are enrolling for the first time or reevaluating your options during Open Enrollment, take the time to read the SBC. It is a small document that can make a big difference in your healthcare experience.
Compare health plans
Finding plans in your area…