Special Enrollment Period for New Parents Health Insurance
The special enrollment period for new parents health insurance gives you 60 days to add your baby. Call 8338648035 for enrollment help.
By Spencer Rothman
Compare health plans
Finding plans in your area…
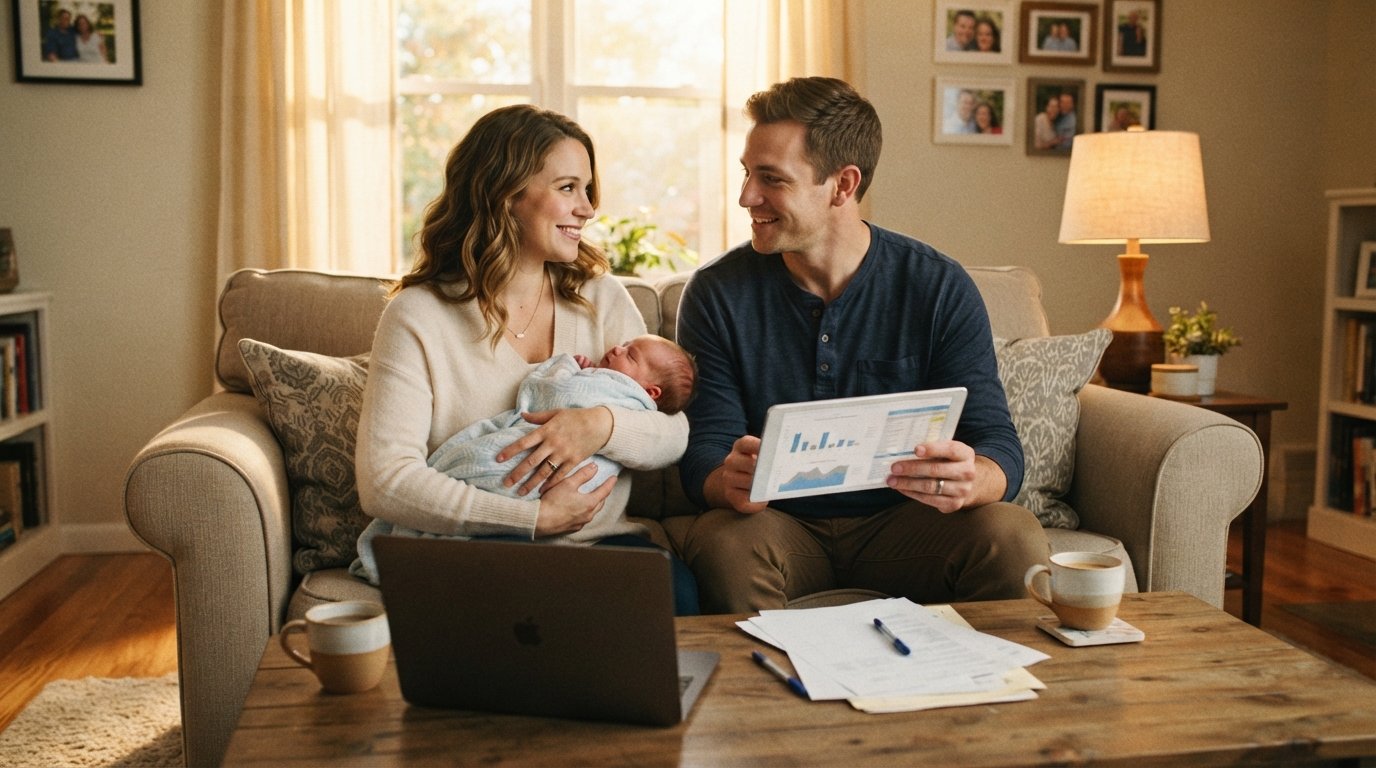
Bringing a new baby into your family is a whirlwind of joy, sleepless nights, and endless paperwork. Among the pediatrician visits and diaper changes, one critical task often gets overlooked: securing health insurance for your newborn and possibly updating your own coverage. The good news is that adding a dependent to your health plan qualifies you for a Special Enrollment Period for new parents health insurance. This window allows you to enroll in a new plan or adjust your existing one outside the standard Open Enrollment timeline.
Understanding how this period works, what documentation you need, and when to act can save you from gaps in coverage and unexpected medical bills. Whether you are self-employed, covered through an employer, or shopping on the ACA Marketplace, the rules are designed to protect growing families. NewHealthInsurance.com specializes in helping parents navigate these transitions quickly, comparing plans from top carriers like Humana, Cigna, and Ambetter Health.
What Triggers a Special Enrollment Period for New Parents?
A Special Enrollment Period (SEP) is a window of time outside the annual Open Enrollment Period when you can sign up for health insurance or make changes to your plan. For new parents, the trigger is a Qualifying Life Event (QLE). The most common QLEs related to growing a family include:
- Giving birth to a child
- Adopting a child
- Placing a child for foster care
- Receiving a court order for legal guardianship
The birth of a child is considered a QLE because it represents a significant change in your household size and financial situation. This change affects your eligibility for subsidies and the type of coverage you need. The SEP gives you a 60-day window from the date of the event to enroll in a new plan or add the baby to your existing coverage.
It is important to note that the SEP applies to both parents. If you and your partner have separate insurance plans, one of you can add the baby to your plan, or you can use this event to switch to a family plan that covers everyone. If you are already enrolled in a Marketplace plan, you can update your application to reflect the new dependent and potentially qualify for higher premium tax credits.
How Long Does the Special Enrollment Period Last?
Timing is everything when it comes to health insurance. For new parents, the Special Enrollment Period generally lasts for 60 days. The clock starts on the date of the birth, adoption, or placement of the child. For example, if your baby is born on March 1, you have until April 30 to enroll in a plan.
However, there is a crucial exception for Medicaid and the Children's Health Insurance Program (CHIP). These programs allow year-round enrollment, so if you qualify based on income, you can apply at any time. For Marketplace plans, the 60-day rule is strict. If you miss the deadline, you may have to wait until the next Open Enrollment Period, which typically runs from November 1 to January 15 in most states.
If you are adding the baby to an employer-sponsored plan, the rules may differ slightly. Most employers require you to notify them within 30 to 60 days of the birth. Failing to do so could mean you have to wait until the next open enrollment period to add your child. Always check with your HR department to confirm the exact deadline.
Steps to Enroll Your Newborn
Enrolling a new baby is a straightforward process if you gather the right documents and act quickly. Here is a step-by-step framework to ensure your child gets coverage without delays.
- Notify your insurance provider or employer: If you have job-based coverage, contact your HR department immediately. They will guide you through the paperwork to add the baby.
- Gather required documents: You will typically need the baby's birth certificate or a hospital-issued proof of birth, your Social Security number, and your policy number.
- Update your Marketplace application: If you have an ACA plan, log into your account and report the new dependent. This will update your subsidy eligibility.
- Choose a plan: If you are switching plans, compare options on NewHealthInsurance.com to find one that covers pediatric care, prescriptions, and your preferred doctors.
- Confirm coverage: Once enrolled, verify that your baby's information is correct and that you have received new insurance cards.
One common mistake parents make is assuming the baby is automatically covered under the mother's plan for the first 30 days. While some plans offer a short grace period, this is not universal. To avoid a lapse in coverage, add your baby as soon as possible. If you need help navigating the enrollment process, you can consult our guide on Special Enrollment Period Health Insurance Rules USA for detailed rules and state-specific nuances.
For personalized assistance, NewHealthInsurance.com offers a simple 3-step process: enter your zip code, complete a short form, and compare matched plans. The entire process takes less than 5 minutes, and you can get expert help by calling (833) 864-8035.
Coverage Options for New Parents
When you welcome a new baby, your health insurance needs shift. You may want a plan with low deductibles, comprehensive pediatric care, and access to a wide network of specialists. The type of plan you choose depends on your budget, your health needs, and whether you qualify for subsidies.
Here are the main plan types to consider during your Special Enrollment Period:
- ACA Marketplace Plans: These plans cover essential health benefits, including maternity and newborn care. If your income falls within certain limits, you may qualify for premium tax credits that reduce your monthly premium.
- Employer-Sponsored Plans: If you have coverage through a job, adding a dependent is often the most cost-effective option, especially if your employer contributes to family premiums.
- Short-Term Health Insurance: These plans are not ACA-compliant and may not cover maternity care or pre-existing conditions. They are generally not recommended for new parents.
- Medicaid and CHIP: If your income is low, your baby may qualify for free or low-cost coverage through these government programs.
When comparing plans, pay attention to the deductible, copays, and out-of-pocket maximum. A plan with a higher premium might save you money in the long run if it covers the services your family needs. NewHealthInsurance.com partners with leading carriers like Anthem, Kaiser Permanente, and Aetna, giving you access to a wide range of options.
If you are considering a private plan, it is helpful to understand how insurance shopping works. Resources like InsuranceShopping provide educational content on comparing policies, which can complement the personalized quote comparison you get from NewHealthInsurance.com.
Common Mistakes to Avoid
Navigating health insurance as a new parent can be overwhelming, and small errors can lead to big headaches. One of the most common mistakes is missing the 60-day deadline. Set a reminder on your phone as soon as the baby is born. Another mistake is failing to update your income information. If your household income has changed, you may be eligible for larger subsidies, but you must report the change to the Marketplace.
Additionally, do not assume that your current plan is the best fit for your growing family. A plan that worked well for a single adult might have high copays for pediatric visits or limited prescription coverage. Take the time to compare at least three plans side by side. Finally, keep copies of all documents you submit. If there is a dispute about coverage, having proof of timely enrollment can be a lifesaver.
If you are feeling stuck, do not hesitate to seek professional help. Licensed agents at NewHealthInsurance.com can answer your questions and guide you through the enrollment process. Call (833) 864-8035 to speak with a certified expert who can help you find a plan that fits your family's needs and budget.
Frequently Asked Questions
Can I add my baby to my plan if I am on a short-term health insurance plan?
Most short-term health insurance plans do not allow you to add dependents after the policy starts. You would need to apply for a new policy that includes the baby, but short-term plans often exclude maternity and newborn care. It is better to switch to an ACA-compliant plan during your Special Enrollment Period.
What if my partner and I are on different plans?
You can choose to add the baby to either parent's plan. If one plan offers better pediatric benefits or lower costs, that might be the better choice. Alternatively, you can use this QLE to enroll in a new family plan that covers everyone under one policy.
Does the Special Enrollment Period apply to dental and vision insurance?
Yes, many dental and vision insurance providers also offer a Special Enrollment Period for new parents. The rules vary by insurer, so it is best to contact them directly. Adding a child to your dental plan is often a good idea, as pediatric dental care is an essential health benefit for ACA plans.
How do I prove the birth for my Special Enrollment Period?
You will need to provide documentation, such as a birth certificate or a letter from the hospital. The Marketplace may ask for a copy of this document to verify your QLE. If you are adding the baby to an employer plan, your HR department will tell you what they need.
Welcoming a new child is a life-changing event, and having the right health insurance ensures you can focus on your family's health and happiness. With the Special Enrollment Period for new parents health insurance, you have the opportunity to secure comprehensive coverage. Take advantage of this window, compare plans, and get the support you need from NewHealthInsurance.com.
Compare health plans
Finding plans in your area…