Primary Care Physician Role in an HMO Plan Explained
Understanding the role of a primary care physician in an HMO plan is key to managing costs and care. Call 8338648035 for expert guidance.
By Dana Whitaker
Compare health plans
Finding plans in your area…
When you enroll in a Health Maintenance Organization (HMO) plan, you are not just buying insurance; you are choosing a specific structure for how you receive medical care. At the center of this structure is the primary care physician (PCP). Unlike indemnity plans or Preferred Provider Organizations (PPOs) where you might see a specialist without a referral, an HMO places your PCP in the role of a gatekeeper. Understanding the role of a primary care physician in an HMO plan is essential for navigating your coverage effectively, avoiding surprise bills, and ensuring you get the right care at the right time. Whether you are looking for a new doctor or trying to understand your benefits, knowing how this relationship works can save you time, money, and stress.
The Primary Care Physician as Your Medical Home
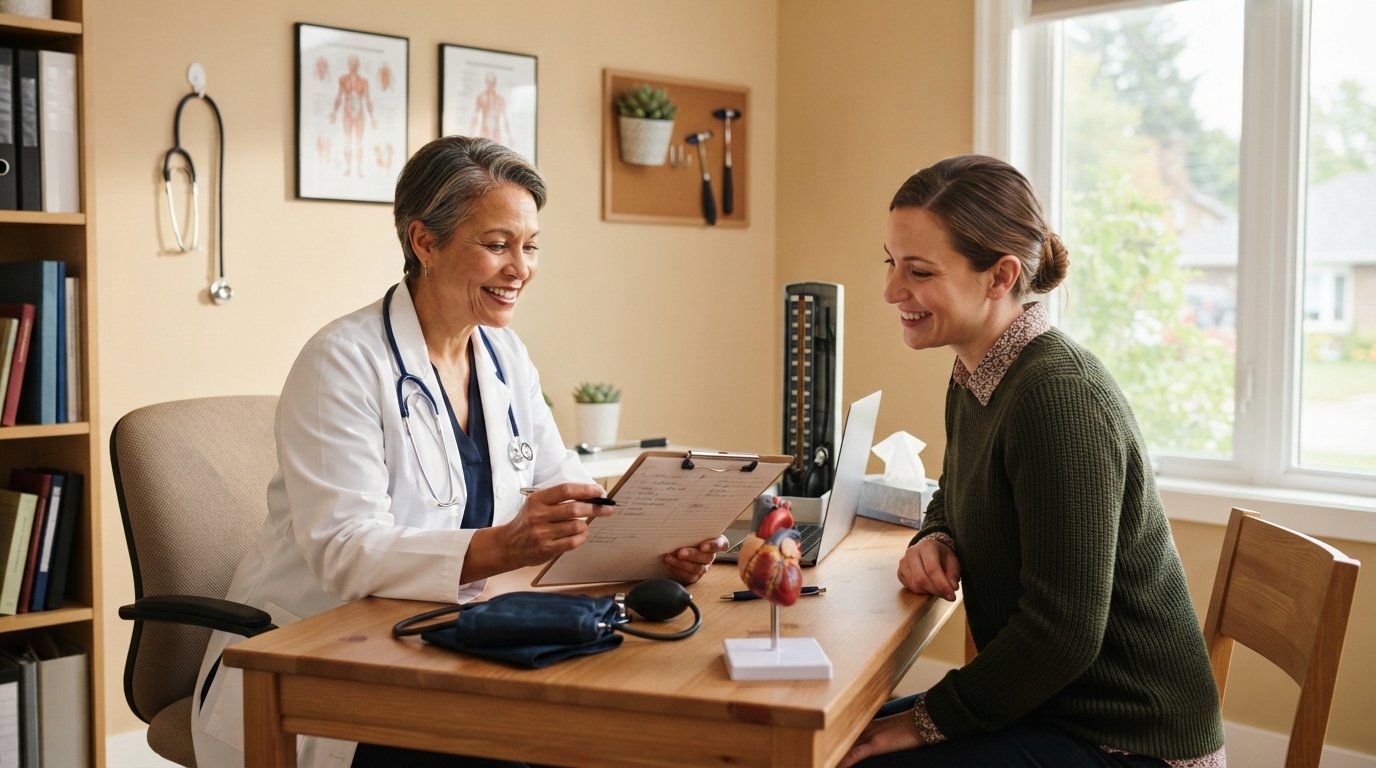
In an HMO plan, your primary care physician serves as your medical home. This means that for almost all of your healthcare needs, your PCP is the first person you contact. They are responsible for managing your overall health, coordinating your care, and maintaining your medical history. This is different from other insurance models where you might visit urgent care clinics or specialists directly without informing your regular doctor. In an HMO, the PCP acts as the central hub for your healthcare information and treatment.
The role of a primary care physician in an HMO plan goes beyond just treating you when you are sick. They are also your partner in preventive care. This includes annual physicals, immunizations, screenings, and general health counseling. Because HMOs focus on preventive care to keep costs down, your PCP is incentivized to help you stay healthy rather than just treating you after you become ill. They monitor your chronic conditions, such as diabetes or high blood pressure, and adjust your treatment plans as needed.
Furthermore, your PCP is responsible for coordinating your care with other providers. If you need to see a cardiologist or a dermatologist, your PCP will typically refer you. This coordination ensures that your specialists have your complete medical history and that there are no conflicting treatments. It also helps the insurance company track your care and ensure that the services you receive are medically necessary and covered under your plan. Without this central coordination, patients might undergo duplicate tests or receive conflicting advice from different doctors.
Referrals and the Gatekeeper System
One of the most defining characteristics of an HMO is the referral system. In most HMO plans, your primary care physician acts as a gatekeeper. This means you generally cannot see a specialist without first obtaining a referral from your PCP. If you attempt to see a specialist without a referral, your HMO may not cover the visit, leaving you responsible for the full cost. This system is designed to manage costs by ensuring that patients receive the appropriate level of care in the most cost-effective setting.
The referral process typically works as follows: You visit your PCP for a specific issue. If the PCP determines that your condition requires specialized care, they will issue a referral to a specialist within the HMO's network. This referral is usually valid for a specific number of visits or a certain period of time. The PCP may also need to obtain prior authorization from the insurance company for certain procedures or treatments. This step ensures that the insurance company agrees the service is necessary before it is performed.
This gatekeeper role is crucial for maintaining the financial viability of the HMO. By preventing unnecessary specialist visits and expensive procedures, the HMO can keep premiums lower for everyone. However, for you as a patient, it means you must be proactive. You need to establish a relationship with your PCP and communicate your symptoms clearly so they can determine if a referral is needed. If you are looking for a new doctor, resources like our guide on finding female primary care doctors can help you identify a provider who fits your preferences and is within your HMO network.
Network Restrictions and Provider Selection
HMO plans operate within a specific network of providers. When you enroll in an HMO, you must choose a primary care physician who is part of that network. This is usually done during the enrollment process or shortly after your coverage begins. You can typically find a list of participating providers on the insurance company's website or by calling their customer service line. It is important to verify that your chosen PCP is accepting new patients and is still in the network at the time you enroll.
Because HMOs do not cover care outside of their network (except in emergencies), staying within the network is critical. Your PCP must be a network provider, and any specialists they refer you to must also be in the network. If you receive care from an out-of-network provider without prior approval, you will likely have to pay the entire bill. This is a significant difference from PPO plans, which offer some coverage for out-of-network care.
However, this restriction comes with a trade-off: lower costs. HMOs typically have lower premiums, deductibles, and copayments compared to other plan types. The role of the primary care physician in an HMO plan is to help you navigate this network efficiently. They know which specialists are available, which hospitals are affiliated, and how to get things done within the system. Building a strong relationship with your PCP can help you get the most out of your HMO coverage.
Cost Implications and Financial Benefits
Understanding the financial aspect of an HMO is essential. Because the HMO manages your care through your PCP, you often pay less out of pocket for services. For example, a visit to your PCP might have a copay of $20, while a visit to a specialist might be $40. Preventive care, such as annual checkups and screenings, is often covered at 100% with no copay. This is a direct result of the HMO's focus on early detection and prevention.
When you use your PCP as your first point of contact, you avoid the higher costs associated with emergency room visits or out-of-network care. The gatekeeper system ensures that you are treated in the most appropriate setting. For instance, if you have a minor illness, your PCP can treat you in their office rather than you going to the ER. This saves both you and the insurance company money.
Additionally, HMOs often have lower out-of-pocket maximums. This means that if you have a major health event, the most you will have to pay in a year is capped at a lower amount than with other plans. This provides financial peace of mind. To explore plans that offer these financial benefits, you can compare options on InsuranceShopping, which provides tools to help you find coverage that fits your budget.
Choosing and Changing Your PCP
Selecting the right primary care physician is one of the most important decisions you will make when joining an HMO. You want a doctor who listens to you, understands your health goals, and is accessible when you need them. Here are some factors to consider when choosing a PCP:
- Location and Hours: Choose a doctor whose office is convenient for you and offers hours that fit your schedule.
- Hospital Affiliations: If you have a preferred hospital, check if your PCP admits patients there.
- Specialties: If you have specific health conditions, look for a PCP with experience in those areas, such as geriatrics or pediatrics.
- Communication Style: Consider whether you prefer a doctor who is direct and efficient or one who takes a more conversational approach.
If you are not happy with your PCP, you can usually change them. Most HMOs allow you to switch primary care physicians by contacting member services or logging into your online account. The change is typically effective the first of the following month. You do not need a reason to change, but it is a good idea to ensure your new doctor is accepting new patients and is in the network.
It is also important to note that if your PCP leaves the network, you will need to choose a new one. The insurance company will usually notify you of this change and provide you with a list of other providers to choose from. During this transition, you may need to request new referrals for any ongoing specialist care.
The PCP's Role in Preventive Care and Chronic Disease Management
In an HMO, the primary care physician plays a critical role in preventive care. They are responsible for ensuring you receive recommended screenings, such as mammograms, colonoscopies, and cholesterol tests. They also provide counseling on lifestyle factors like diet, exercise, and smoking cessation. By catching health issues early, they can help you avoid more serious and costly complications down the road.
For those with chronic conditions, the PCP acts as the manager of your care team. They monitor your condition, adjust medications, and coordinate with specialists. For example, if you have diabetes, your PCP will monitor your blood sugar levels and refer you to an endocrinologist if needed. They will also ensure you receive regular eye exams and foot care, which are essential for managing diabetes.
This continuity of care is a major advantage of the HMO model. Because your PCP has your complete medical history, they can make more informed decisions about your treatment. They can also identify patterns or potential issues that a specialist might miss if they only see you for a specific problem. This holistic approach to healthcare is one of the key benefits of having a dedicated primary care physician.
Emergency Care and Urgent Situations
While HMOs require you to go through your PCP for most care, there are exceptions for emergencies. If you have a life-threatening emergency, you should call 911 or go to the nearest emergency room. You do not need a referral for emergency care, and your HMO will cover the treatment. However, you should notify your PCP as soon as possible after the emergency so they can follow up on your care.
For urgent but non-life-threatening situations, many HMOs offer urgent care centers or nurse advice lines. These services can help you get care quickly without going to the ER. Some HMOs also allow you to visit an urgent care center without a referral, while others may require you to contact your PCP first. It is important to read your plan's details to understand the rules for urgent care.
In all cases, the role of the primary care physician in an HMO plan is to ensure you receive the right care in the right setting. They are your advocate within the healthcare system, helping you navigate the complexities of insurance and medical treatment. By building a strong relationship with your PCP, you can ensure you get the most out of your HMO plan.
Conclusion
Navigating an HMO plan requires a clear understanding of the primary care physician's role. From acting as a gatekeeper for referrals to coordinating your overall care, your PCP is central to your healthcare experience. By choosing a doctor you trust and following the plan's rules, you can enjoy lower costs and comprehensive coverage. If you are looking for an HMO plan or need help understanding your options, NewHealthInsurance.com can help you compare plans and find the right fit for your needs. Call us at 8338648035 to get started.
Compare health plans
Finding plans in your area…