PHCS MultiPlan PPO Network: What It Is and How It Works
PHCS MultiPlan is a provider network, not insurance. Call (833)-864-8035 to compare plans that use it and maximize your savings.
By Jordan Blackwell
Compare health plans
Finding plans in your area…
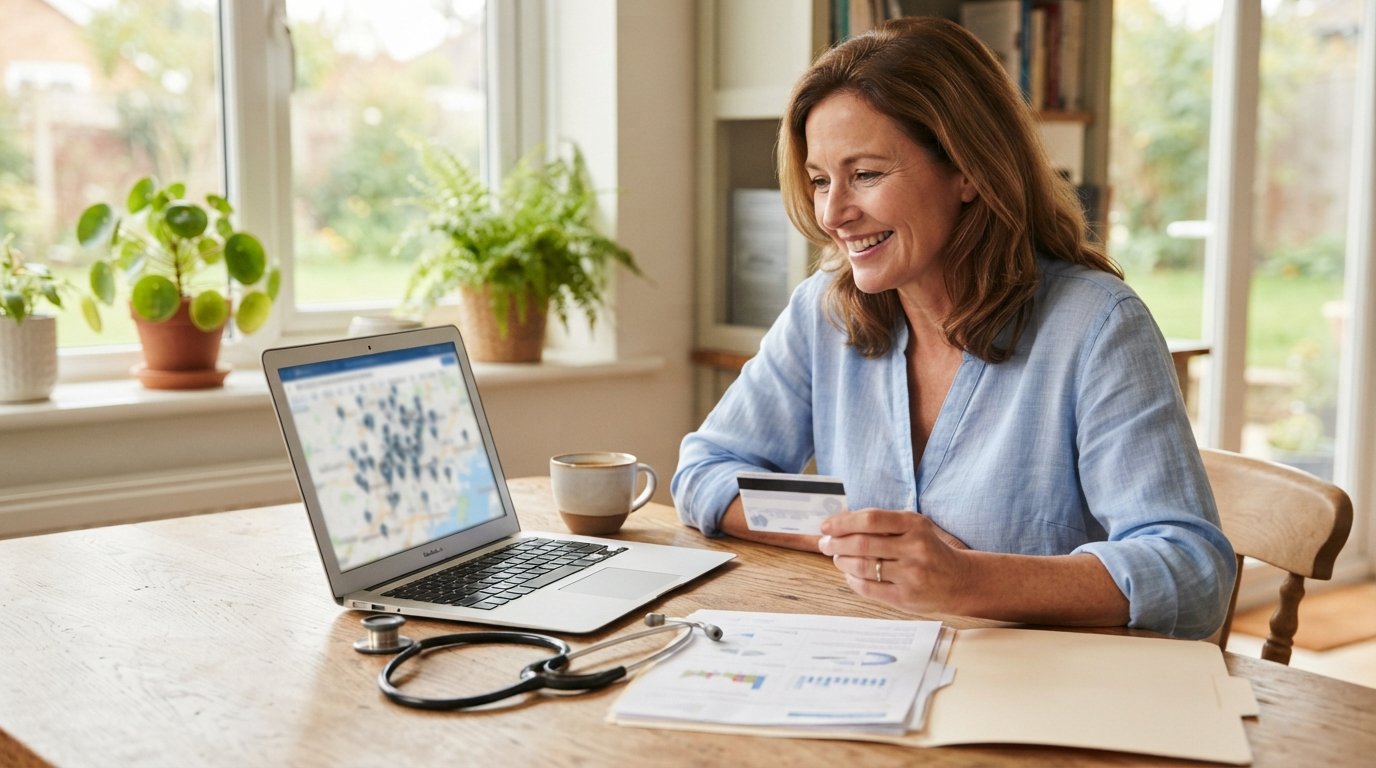
You open your health insurance card, glance at the logo, and notice two names you do not recognize: PHCS and MultiPlan. A wave of confusion hits. Is this your actual insurance company? Did you accidentally enroll in some obscure plan? The good news is that you are not alone, and the situation is far less complicated than it looks. Understanding what a PHCS MultiPlan PPO network is and how it works can save you from costly mistakes, surprise bills, and unnecessary stress when you need medical care.
At its core, PHCS MultiPlan is not an insurance company. It is a provider network, a behind-the-scenes infrastructure that connects you to doctors and hospitals at negotiated rates. Think of it as a bridge between your health plan and the medical providers you visit. Your actual insurance carrier uses this network to give you access to discounted care. Once you grasp this distinction, the fog begins to clear, and you can navigate your benefits with confidence. If you are comparing health plans and want to know whether a PHCS MultiPlan network plan fits your needs, the experts at USLifeQuote can help you evaluate your options and find coverage that aligns with your budget and healthcare habits.
PHCS MultiPlan Is a Provider Network, Not an Insurance Company
The single most important fact to internalize is that PHCS MultiPlan does not sell insurance. It does not collect your premiums, set your deductible, or decide whether a claim is covered. Instead, it is a network of doctors, hospitals, specialists, and other healthcare providers who have agreed to offer services at discounted rates to members of health plans that contract with MultiPlan. Your insurance carrier (the company whose name appears on your premium bill) rents access to this network so that you can see a broad range of providers without paying full price.
This arrangement is common in the health insurance industry. Carriers often lease networks from third-party companies like MultiPlan to expand their provider reach without having to negotiate individual contracts with every doctor in the country. When you see PHCS MultiPlan on your card, it means your specific health plan uses this network to determine which providers are considered in-network for you. The PHCS portion stands for Private Healthcare Systems, a network brand that MultiPlan acquired years ago. Today, the terms PHCS and MultiPlan are often used interchangeably, though PHCS generally refers to the specific PPO network product.
The distinction matters because it affects how you shop for care and how your claims are processed. If you misunderstand the role of PHCS MultiPlan, you might mistakenly call them to ask about your deductible or to dispute a denied claim. Those inquiries belong to your insurance carrier, not the network. Keeping this separation clear in your mind will streamline every interaction you have with the healthcare system.
How the PHCS MultiPlan PPO Network Works for Members
When you enroll in a health plan that uses the PHCS MultiPlan PPO network, you gain access to a large group of participating providers. These providers have agreed to accept negotiated rates for their services, which are typically lower than their standard billed charges. In exchange, the network directs patient volume their way. As a member, your primary benefit is cost savings: you pay the negotiated rate (often just a copay or coinsurance) rather than the full retail price.Here is the step-by-step process of how a claim typically flows through the network:
- You visit a provider. Before your appointment, you confirm that the provider participates in the PHCS MultiPlan network. You present your insurance card, which includes both your carrier's information and the network logo.
- The provider verifies eligibility. The provider's office contacts your insurance carrier (or the network) to confirm your coverage and benefits. This step ensures that the provider knows you are an eligible member and can apply the correct network discounts.
- Services are rendered and coded. After your visit, the provider submits a claim to your insurance carrier with the appropriate medical codes and charges. The claim includes the network discount applied according to the provider's contract with PHCS MultiPlan.
- Your carrier processes the claim. Your insurance company applies your plan's rules: deductible, copay, coinsurance, and out-of-pocket maximum. They pay their share to the provider and send you an Explanation of Benefits (EOB) detailing what was covered and what you owe.
- You receive a bill for your portion. The provider bills you for any remaining balance (your copay, coinsurance, or amount toward your deductible). Because the provider is in-network, they have agreed not to bill you for more than the negotiated rate, protecting you from balance billing in most cases.
This flow works smoothly when you stay in-network. The complexity arises when you see an out-of-network provider or when a service requires prior authorization. Understanding these nuances is essential to maximizing your benefits and avoiding financial surprises.
In-Network vs. Out-of-Network: What It Really Means
The term in-network simply means that a provider has a contract with the PHCS MultiPlan network. When you see an in-network provider, your insurance plan applies its negotiated rates and typically offers better coverage: lower deductibles, lower copays, and lower coinsurance. Out-of-network providers have no such contract, so they can bill you at their full rate, and your insurance may cover little or nothing. In some cases, out-of-network care is not covered at all except for emergencies.
It is important to note that network participation can vary by location and by specific provider group. A doctor's office might participate in PHCS MultiPlan, but the lab they use for blood work might not. Similarly, a hospital might be in-network, but the anesthesiologist or radiologist who treats you could be out-of-network. This scenario, known as surprise billing, has been addressed by federal regulations in recent years, but gaps remain. Always verify not just the facility but also the individual providers who will treat you.
Another key point: PHCS MultiPlan PPO networks typically offer out-of-network benefits, though at a higher cost. This flexibility is a hallmark of PPO plans. You can see out-of-network providers, but you will pay more: a higher deductible, higher coinsurance, and potentially the difference between the provider's charge and the allowed amount. Some plans also require you to meet a separate out-of-network deductible before any coverage kicks in. Reading your plan documents carefully will clarify these details.
Typical Discounts and How Claims Route Through MultiPlan
The discounts negotiated by PHCS MultiPlan can be substantial, often ranging from 20% to 50% or more off standard provider charges. However, the exact discount depends on the provider's contract and the type of service. These discounts are not automatic for everyone; they apply only to members of health plans that have contracted with MultiPlan. If you have a PHCS MultiPlan logo on your card, you are entitled to those discounts when you see participating providers.
Claims routing is a critical behind-the-scenes process. When a provider submits a claim, it goes to your insurance carrier, not to MultiPlan directly. Your carrier then applies the network discount according to its agreement with MultiPlan. In some cases, the provider may submit the claim to MultiPlan first, which then reprices the claim and forwards it to your carrier. Either way, the end result is the same: the negotiated discount is applied before your benefits are calculated. This is why using in-network providers is so important: the discount reduces the total cost of care, which in turn reduces your out-of-pocket responsibility.
It is worth noting that MultiPlan also offers other network brands beyond PHCS, such as MultiPlan PPO and Beech Street. These networks may have different provider compositions and discount levels. Your specific plan might use one or more of these networks. The logo on your card tells you which network to reference when searching for providers.
Who Commonly Uses PHCS MultiPlan Plans?
PHCS MultiPlan networks are used by a wide variety of health plans, including individual and family plans, employer-sponsored group plans, and even some Medicare Advantage plans. They are particularly common in plans sold on the individual market, including short-term health insurance and fixed indemnity plans. Because MultiPlan is a rental network, it allows smaller insurance carriers to offer broad provider access without building their own network from scratch. This is especially beneficial for consumers who want flexibility and choice.
Self-funded employer plans also frequently use PHCS MultiPlan to administer their benefits. In a self-funded arrangement, the employer pays claims directly but uses the network to negotiate discounts and process claims. If you work for a mid-sized or large company, there is a good chance your plan uses a rental network like PHCS MultiPlan, even if the logo is not prominently displayed.
If you are shopping for health insurance and want to know whether a plan uses the PHCS MultiPlan network, check the plan details or ask the carrier directly. Brokers like NewHealthInsurance.com can help you compare plans and identify which networks they use, ensuring that your preferred doctors and hospitals are covered. You can also use our guide to how a healthcare FSA works to understand how to pair a network plan with tax-advantaged savings for medical expenses.
How to Verify a Provider Is In-Network
Verifying network participation is one of the most important steps you can take to avoid surprise bills. Do not assume that a provider is in-network just because they accepted your plan in the past; networks change, and providers may leave or join at any time. Here is a simple process to follow:
- Check your insurance card. Look for the PHCS or MultiPlan logo. This tells you which network to search.
- Use the online provider directory. Visit the MultiPlan website or your insurance carrier's member portal to search for your provider by name and location. The directory is updated regularly, but it is still wise to confirm with the provider's office.
- Call the provider's office. Ask specifically: "Are you participating in the PHCS MultiPlan network?" Also ask about any affiliated providers (labs, imaging centers, anesthesiologists) who might be involved in your care.
- Call your insurance carrier. Confirm benefits and network status with your carrier's member services team. They can also tell you if prior authorization is required for your service.
- Document your findings. Keep a record of the date, the name of the representative you spoke with, and what they told you. This documentation can be invaluable if a billing dispute arises later.
Following these steps takes a few minutes but can save you hundreds or even thousands of dollars. It also gives you peace of mind knowing that you have done your due diligence. When in doubt, always err on the side of caution and verify again closer to your appointment date.
Common Misconceptions About PHCS MultiPlan
One widespread misconception is that PHCS MultiPlan is a government program or an ACA Marketplace plan. It is neither. It is a private network used by many different types of plans. Another misconception is that having a PHCS MultiPlan card means you have comprehensive coverage. The network only provides access to discounted providers; your actual benefits are determined by your insurance policy. You could have a PHCS MultiPlan card with a plan that offers minimal benefits, such as a short-term policy that does not cover pre-existing conditions.
A third misconception is that PHCS MultiPlan discounts apply to everyone, even without insurance. That is not true. The discounts are contractually reserved for members of participating health plans. If you do not have insurance that uses the network, you cannot simply show a PHCS card and expect the discount. Finally, some people believe that MultiPlan is an insurance carrier that pays claims. It does not; it only reprices claims and routes them to the responsible payer.
Clearing up these misunderstandings helps you use your benefits correctly and communicate effectively with providers and your insurance company. It also prevents frustration when you encounter billing issues or need to explain your coverage to a new doctor.
Making the Most of Your PHCS MultiPlan PPO Coverage
To get the most value from your PHCS MultiPlan PPO plan, stay in-network whenever possible. Use preventive care services, which are often covered at no cost, to catch health issues early and avoid more expensive treatments later. Understand your plan's deductible, copay, and coinsurance structure so you can budget for out-of-pocket costs. If you need a costly procedure, ask your provider for a pre-service cost estimate and compare it against your benefits.
Also, take advantage of tools offered by your insurance carrier and MultiPlan, such as cost estimators and provider directories. These resources empower you to make informed decisions. If you have a chronic condition or require ongoing treatment, confirm that your specialists and preferred hospitals are in-network before you enroll in a plan. A little research upfront can prevent significant financial strain down the road.
Finally, remember that you are not alone in navigating this complexity. Licensed insurance professionals can help you understand your options, verify network participation, and choose a plan that fits your needs. Whether you are enrolling for the first time or reevaluating your coverage during Open Enrollment, expert guidance is just a phone call away.
Understanding what a PHCS MultiPlan PPO network is and how it works transforms confusion into clarity. It is a tool that connects you to discounted care through your insurance plan, not a substitute for insurance itself. By verifying providers, knowing your benefits, and staying in-network, you can maximize savings and access the care you need with confidence.
Compare health plans
Finding plans in your area…