Multi-State Health Insurance Plans for Remote Workers
Multi-state health insurance plans for remote workers keep you covered across state lines. Call 8338648035 for expert help finding the right plan.
By Talia Rosenfield
Compare health plans
Finding plans in your area…
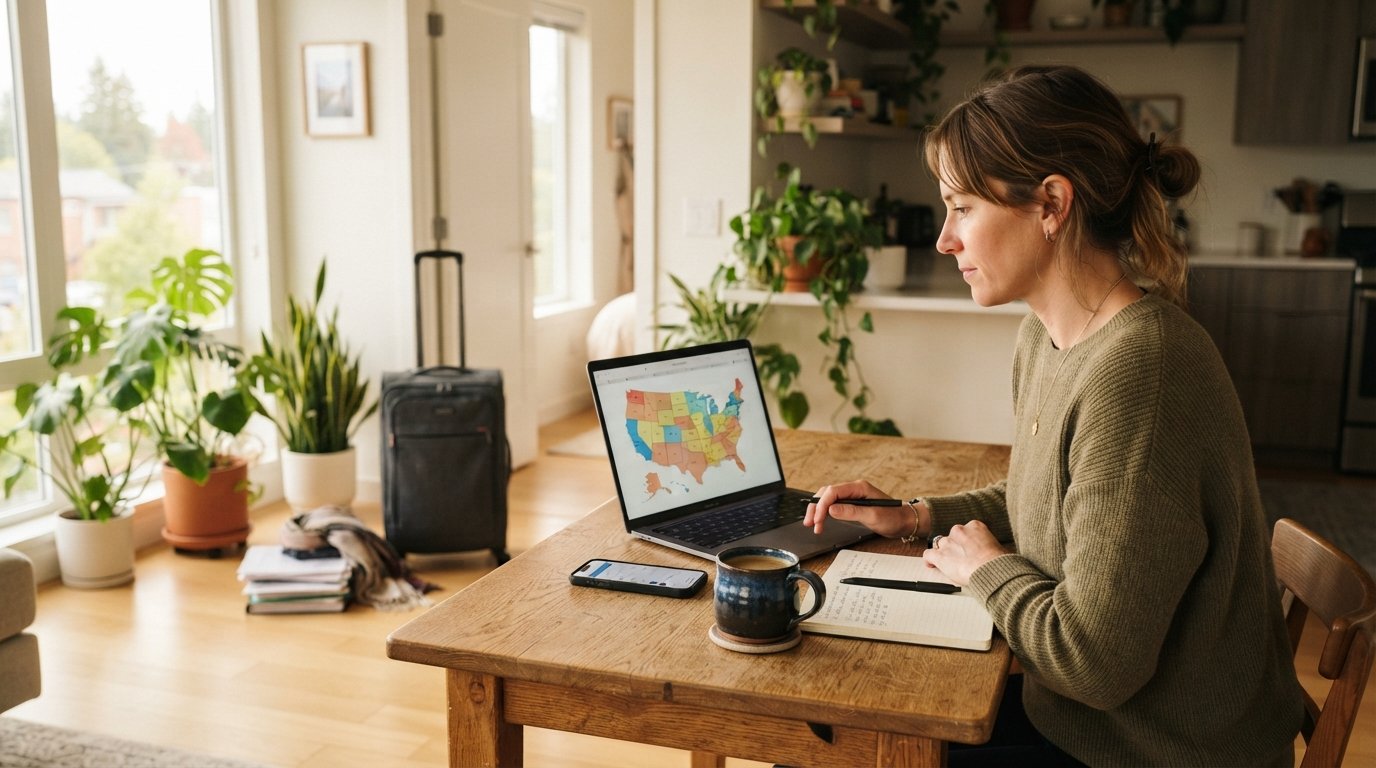
Working remotely from three different states in a single year sounds like freedom until you need to see a doctor. A sudden ear infection in Austin, a routine checkup while visiting family in Ohio, or a specialist referral in Denver can turn into a billing nightmare if your health plan only works within one narrow service area. That is why multi-state health insurance plans for remote workers have become one of the fastest-growing coverage questions in the individual market. The good news: options exist, and with the right guidance, you can build a plan that follows you instead of holding you back.
The core challenge is that most traditional health insurance networks are built around geography. An HMO in Florida may refuse to cover non-emergency care in Oregon. A short-term plan purchased in Texas may exclude providers in California entirely. Multi-state plans solve this by using national networks, telehealth-first designs, or employer-style PPO structures that reimburse care across state lines. The trick is knowing which type fits your travel pattern, your budget, and your health needs.
Why Remote Workers Need Multi-State Coverage
Remote work has quietly rewritten the rules of where people live. According to census and labor data, millions of Americans now split their time between a home base and one or more temporary locations. Some are digital nomads bouncing between co-working hubs. Others are caregivers who spend winters near aging parents in Arizona and summers at a family home in Michigan. A few are simply testing new cities before committing to a permanent move. Each scenario creates the same insurance problem: your body travels, but your network does not.
Standard ACA Marketplace plans are state-specific. If you enroll in a New York plan, your coverage is generally valid for emergencies nationwide, but routine care outside New York may be out-of-network or not covered at all. That works fine for someone who rarely leaves Brooklyn. It fails for a remote worker who spends two months in North Carolina and three weeks in Colorado. Multi-state health insurance plans for remote workers bridge that gap by offering provider access in multiple states or by leaning heavily on virtual care that ignores state borders for most common conditions.
There is also a financial angle. Out-of-network care can trigger surprise bills, balance billing, and deductibles that do not count toward your in-network maximum. A single out-of-state emergency room visit can cost thousands more than the same visit at home. Multi-state plans reduce that risk by expanding your network or by making telehealth your primary point of care, which keeps costs predictable no matter where you open your laptop.
Types of Multi-State Health Insurance Plans for Remote Workers
Not all multi-state coverage is built the same way. The right choice depends on how often you travel, whether you need specialist care, and how much you want to pay each month. Here are the main categories worth understanding before you compare quotes.
- National PPO plans: These use large provider networks that include doctors and hospitals in every state. You can see specialists without a referral and usually pay in-network rates nationwide. Premiums are higher, but flexibility is unmatched.
- ACA Marketplace plans with multi-state networks: Some insurers offer Marketplace plans that contract with providers in neighboring states or across a region. These are less common but valuable if you split time between two specific states.
- Telehealth-first plans: These plans emphasize virtual visits for primary care, mental health, and prescriptions. They often include a national network for labs and urgent care, making them a strong fit for remote workers who rarely need in-person specialty care.
- Short-term medical plans: Designed for gaps in coverage, these can sometimes be used across state lines, but benefits vary widely. They are not ACA-compliant and may exclude pre-existing conditions.
- Employer-sponsored PPO or EPO plans: If you work for a company with a national carrier, your plan may already cover you in multiple states. Always confirm the network before you travel.
Each option has trade-offs. National PPOs cost more but offer the fewest surprises. Telehealth-first plans are affordable and convenient but may not work for complex conditions. Short-term plans are cheap but risky for anyone with ongoing health needs. The best approach is to match the plan type to your actual travel and care patterns, not to a hypothetical worst-case scenario.
If you are also managing mental health care, it helps to understand how coverage works across state lines. Our guide on mental health coverage health insurance USA plans explains how to verify therapists, psychiatrists, and prescription coverage when you live in more than one place.
How to Compare Multi-State Plans Step by Step
Comparing multi-state health insurance plans for remote workers is not the same as comparing local plans. You need to check network reach, telehealth rules, prescription coverage, and how the plan handles out-of-state claims. A plan that looks affordable on a quote screen can become expensive if it excludes the specialists you need.
Start by listing the states where you spend the most time. Then list the providers you cannot give up: a primary care doctor, a therapist, a cardiologist, or a pharmacy. Next, check each plan's provider directory for those specific names and locations. Do not assume that a national carrier means every doctor is in-network. Networks vary by plan, not just by insurer.
Here is a practical framework you can follow:
- Map your travel: Write down every state you will spend more than two weeks in during the next 12 months.
- List must-have providers: Identify the doctors, therapists, and pharmacies you want to keep.
- Check network directories: Verify each provider is in-network in every relevant state.
- Review telehealth benefits: Confirm whether virtual visits are covered and whether they count toward your deductible.
- Compare total costs: Add premiums, deductibles, copays, and expected out-of-pocket costs, not just the monthly price.
After you narrow your list, call the insurer and ask two questions: Is my provider in-network in State A and State B? And how are out-of-state claims processed? Get the answers in writing if possible. This simple step prevents most billing surprises.
State-Specific Rules That Affect Remote Workers
Health insurance is regulated state by state, which means a plan that works in one state may not be available in another. Some states require insurers to offer multi-state networks. Others allow them but do not mandate them. A few states have their own marketplaces and subsidies that interact with federal rules in ways that affect remote workers.
For example, if you move from California to Texas, you may need to cancel your California Marketplace plan and enroll in a Texas plan during a special enrollment period. If you split time between two states, you may need to choose one state as your primary residence and enroll there. Some insurers offer plans that cover you in both states, but you must confirm this before you enroll.
Medicaid is even more restrictive. It is state-specific and generally does not travel with you. If you qualify for Medicaid in one state, you may lose coverage when you establish residency in another. Remote workers with low incomes should factor this into their planning, especially if they move frequently.
Employer-sponsored plans follow federal rules under ERISA, which can make them more portable than individual plans. If your employer offers a national PPO, you may already have multi-state coverage without realizing it. Check your plan documents or call your HR department before you buy a separate policy.
Costs and Subsidies for Multi-State Coverage
Multi-state plans often cost more than single-state plans because they offer broader networks. That said, subsidies under the Affordable Care Act can reduce premiums significantly for households earning between 100% and 400% of the federal poverty level. Some states also offer additional subsidies for middle-income households.
If you are self-employed or a freelancer, you may be able to deduct health insurance premiums from your taxable income. That can offset some of the higher cost of a multi-state plan. If you work for an employer that offers a stipend for health insurance, you can use that money to buy a Marketplace plan that fits your travel pattern.
Short-term plans are usually cheaper but offer fewer protections. They may exclude pre-existing conditions, cap annual benefits, and deny coverage for services you need. They can be a temporary bridge, but they are not a long-term solution for most remote workers.
When you compare plans, look at the total cost of care, not just the premium. A plan with a $0 premium but a $10,000 deductible may cost more than a plan with a $300 premium and a $3,000 deductible if you need regular care. Use a spreadsheet or an online calculator to estimate your annual costs based on your expected visits, prescriptions, and procedures.
When to Enroll and How to Avoid Gaps
Enrollment timing matters. The annual Open Enrollment Period for ACA Marketplace plans typically runs from November 1 to January 15 in most states. If you miss that window, you need a qualifying life event to enroll outside of it. Common qualifying events include moving to a new state, losing employer coverage, getting married, having a baby, or changing income in a way that affects subsidy eligibility.
If you are moving frequently, you may qualify for a special enrollment period each time you establish residency in a new state. That gives you a 60-day window to enroll in a new plan. Do not wait until the last minute. Coverage gaps can leave you responsible for full medical bills if something happens during the transition.
If you are unsure whether you qualify for a special enrollment period, call your state Marketplace or a licensed broker. They can confirm your eligibility and help you enroll before the deadline. Keep documentation of your move, such as a lease, utility bill, or driver's license, in case the Marketplace asks for proof.
Practical Tips for Managing Coverage on the Road
Once you have a multi-state plan, a few habits can make it easier to use. First, save your insurance card digitally and keep a paper copy in your wallet. Second, use in-network urgent care centers instead of emergency rooms for non-emergencies. Third, call ahead to confirm that a provider is in-network before you book an appointment. Fourth, use telehealth for routine visits whenever possible. It is often cheaper and faster than an in-person visit.
If you need to see a specialist in another state, ask your primary care doctor for a referral to an in-network specialist. If no in-network specialist is available, ask the insurer for a network exception or a single-case agreement. Some insurers will approve out-of-network care if you can show that no in-network provider can meet your needs.
Finally, review your plan every year. Networks change, formularies change, and premiums change. A plan that worked well last year may not be the best fit this year. Set a reminder in October to review your options before Open Enrollment begins.
For a broader look at how to compare policies, check trusted resources like InsuranceShopping, which offers educational guides and comparison tools for health, life, and Medicare coverage.
Finding the Right Plan for Your Lifestyle
Multi-state health insurance plans for remote workers are not one-size-fits-all. The right plan depends on where you travel, how often you need care, and how much you want to spend. National PPOs offer the most flexibility but cost more. Telehealth-first plans are affordable and convenient but may not cover complex care. Marketplace plans with multi-state networks can work well if you split time between two specific states.
Before you enroll, verify your providers, check the network, and estimate your total costs. If you need help, licensed brokers and comparison platforms can simplify the process. NewHealthInsurance.com, for example, offers real-time quotes, state-specific guidance, and enrollment assistance for ACA Marketplace, Medicare, and short-term plans. You can compare plans in minutes and get help choosing coverage that works across state lines.
Remote work gives you the freedom to live and work where you want. The right health insurance plan should give you the freedom to get care where you need it, without worrying about surprise bills or coverage gaps. Take the time to compare multi-state options, ask the right questions, and choose a plan that follows you, not one that holds you back.
Compare health plans
Finding plans in your area…