How to Read Your Car Insurance Policy Document in Amazon
Master how to read car insurance policy document in amazon with our step-by-step guide. Call (833)-864-8035 for expert help with your coverage questions.
Compare health plans
Finding plans in your area…
You have just downloaded your car insurance policy document from Amazon, and now you are staring at a PDF that looks like it was written in a foreign language. You are not alone. Thousands of drivers store their auto insurance documents in Amazon Drive or receive them as attachments from carriers, and the dense legal language can feel overwhelming. But here is the good news: reading a car insurance policy document does not require a law degree. With a simple roadmap, you can decode the key sections, spot potential gaps in coverage, and make smarter decisions about your protection. This guide walks you through the entire document, from the declarations page to the exclusions, so you can read your policy with confidence and avoid costly surprises after an accident.
Start With the Declarations Page: Your Policy at a Glance
The declarations page, often called the dec page, is the first section you should read. Think of it as the executive summary of your policy. It lists the most important details in a snapshot: your name, the policy number, the effective dates, the vehicles covered, and the types of coverage you purchased along with their limits. This page is your quick reference for verifying that the information is accurate. If your address is wrong or a vehicle is missing, you will want to correct it immediately with your insurer.
On the dec page, you will also see the premium breakdown. This shows how much you are paying for each coverage type, such as liability, collision, and comprehensive. Understanding this breakdown helps you see where your money is going and whether you might adjust your coverage to save money. For example, if you have an older car, you might consider dropping collision coverage to reduce your premium. The declarations page gives you the data you need to have that conversation.
If you are also managing health insurance documents, the same principle applies: start with the summary page. For a deeper dive into decoding insurance terminology across policy types, our guide on decoding your insurance policy terms can help you master the jargon. But for now, focus on the auto policy dec page and verify every detail before moving on.
Understand the Coverage Sections: What Is Covered and How Much
After the declarations page, the policy document breaks down each coverage type in detail. This is where you learn exactly what your insurer will pay for and under what circumstances. The main coverage types you will typically see are liability, collision, comprehensive, medical payments or personal injury protection, and uninsured or underinsured motorist coverage. Each section explains the coverage, the limits, and any conditions that apply.
Liability coverage is usually split into two parts: bodily injury and property damage. You will see limits expressed as three numbers, such as 100/300/50. This means $100,000 per person for bodily injury, $300,000 total per accident for bodily injury, and $50,000 for property damage. These limits are the maximum your insurer will pay, so choosing adequate limits is crucial to protect your assets. Collision coverage pays for damage to your own vehicle regardless of fault, while comprehensive covers non-collision events like theft, fire, or weather. Medical payments coverage handles medical expenses for you and your passengers, regardless of fault.
To make sense of these sections, use this numbered framework:
- Identify the coverage name and its purpose. Read the first paragraph of each section to understand what the coverage does.
- Locate the limits and deductibles. These are the dollar amounts that determine how much you pay out of pocket and how much the insurer pays.
- Note any conditions or exclusions. Each coverage section may list specific situations where coverage does not apply.
- Check for endorsements. Endorsements are add-ons that modify the standard coverage, and they are often listed after the main coverage sections.
By following this framework, you can systematically extract the key information from each coverage section without getting lost in legal language. Remember that the specific terms and limits vary by insurer and state, so always read the definitions and conditions carefully.
Read the Exclusions: What Your Policy Will Not Cover
Exclusions are the part of the policy that tells you what is not covered. This section is just as important as the coverage sections, because it helps you avoid assuming you have protection when you do not. Common exclusions in auto policies include using your vehicle for commercial purposes (like ride-sharing or delivery), intentional damage, racing, and driving outside the geographic area specified in the policy. Some policies also exclude coverage for certain drivers or vehicles.
When reading the exclusions, pay attention to the language. Words like "we do not cover" or "this policy does not apply to" are clear signals. If you see an exclusion that could affect your situation, such as using your car for business, you may need to purchase additional coverage or a commercial policy. Do not skip this section; it is your best defense against denied claims.
Additionally, exclusions can interact with other parts of the policy. For example, an exclusion for racing might also affect your eligibility for accident forgiveness or safe driver discounts. Always consider how exclusions might impact your overall coverage and premium. If you are unsure about an exclusion, call your insurer and ask for clarification. It is better to ask now than to discover a gap after an accident.
Decode the Definitions and Conditions: The Fine Print That Matters
Every policy document includes a definitions section, usually near the beginning or end, that explains how the insurer interprets key terms. Terms like "insured," "occurrence," "actual cash value," and "reasonable repair" have specific meanings that can significantly affect your claim. For example, "actual cash value" means the insurer will pay the depreciated value of your car, not the replacement cost. If you want replacement cost coverage, you may need to purchase an endorsement.
The conditions section outlines your responsibilities as the policyholder. This includes things like reporting a claim promptly, cooperating with the investigation, and protecting your vehicle from further damage. Failure to comply with these conditions can give the insurer grounds to deny a claim. For instance, if you delay reporting an accident for several weeks, the insurer might argue that it was prejudiced by the delay. Reading the conditions helps you understand what you must do to keep your coverage valid.
While auto and health insurance are different products, the need to understand policy conditions is universal. If you also manage health coverage, our guide on decoding insurance policy terms can help you navigate those documents as well. The key is to treat the definitions and conditions as a contract: they define the rules of the game, and knowing them puts you in control.
Check Endorsements and Riders: Customizing Your Policy
Endorsements, sometimes called riders, are amendments to your policy that add, remove, or modify coverage. They are usually listed on the declarations page and described in detail later in the document. Common auto endorsements include roadside assistance, rental reimbursement, gap coverage, and accident forgiveness. Each endorsement has its own terms and conditions, so read them carefully to understand what you are getting.
For example, gap coverage pays the difference between what you owe on your car loan and the actual cash value of your vehicle if it is totaled. This can be valuable if you have a large loan balance. Rental reimbursement covers the cost of a rental car while yours is being repaired. Accident forgiveness prevents your premium from increasing after your first at-fault accident. These endorsements can be worth the extra premium, but only if they match your needs.
When reviewing endorsements, ask yourself: Does this coverage fill a gap in my standard policy? Is the cost reasonable compared to the benefit? Would I be comfortable paying for this out of pocket? If the answer to the last question is yes, you might skip the endorsement. But if the potential cost is high, the endorsement could provide peace of mind. Always compare the cost of the endorsement to the potential out-of-pocket expense.
Review the Cancellation and Renewal Terms
The cancellation and renewal section explains the rules for ending your policy or keeping it active. It covers notice periods, refunds, and the circumstances under which the insurer can cancel or non-renew your policy. For example, most policies require a certain number of days' notice before cancellation, and you may be entitled to a pro-rated refund of unused premium. Understanding these terms helps you avoid lapses in coverage, which can lead to higher premiums or legal penalties.
Renewal terms are equally important. Some policies automatically renew, while others require you to take action. The renewal section will tell you how and when your premium may change, and what happens if you do not pay on time. If you are considering switching insurers, knowing the cancellation terms can save you money and hassle. For instance, if you cancel mid-term, you might face a short-rate cancellation penalty, which means you get less of a refund than you might expect.
Additionally, the cancellation section may outline your rights if the insurer cancels your policy. In many states, insurers must provide a written explanation and a grace period. Knowing your rights can help you respond effectively if you receive a cancellation notice. Always keep a copy of your policy documents, whether in Amazon Drive or another secure location, so you can refer to them when needed.
Practical Tips for Reading Your Policy Document in Amazon
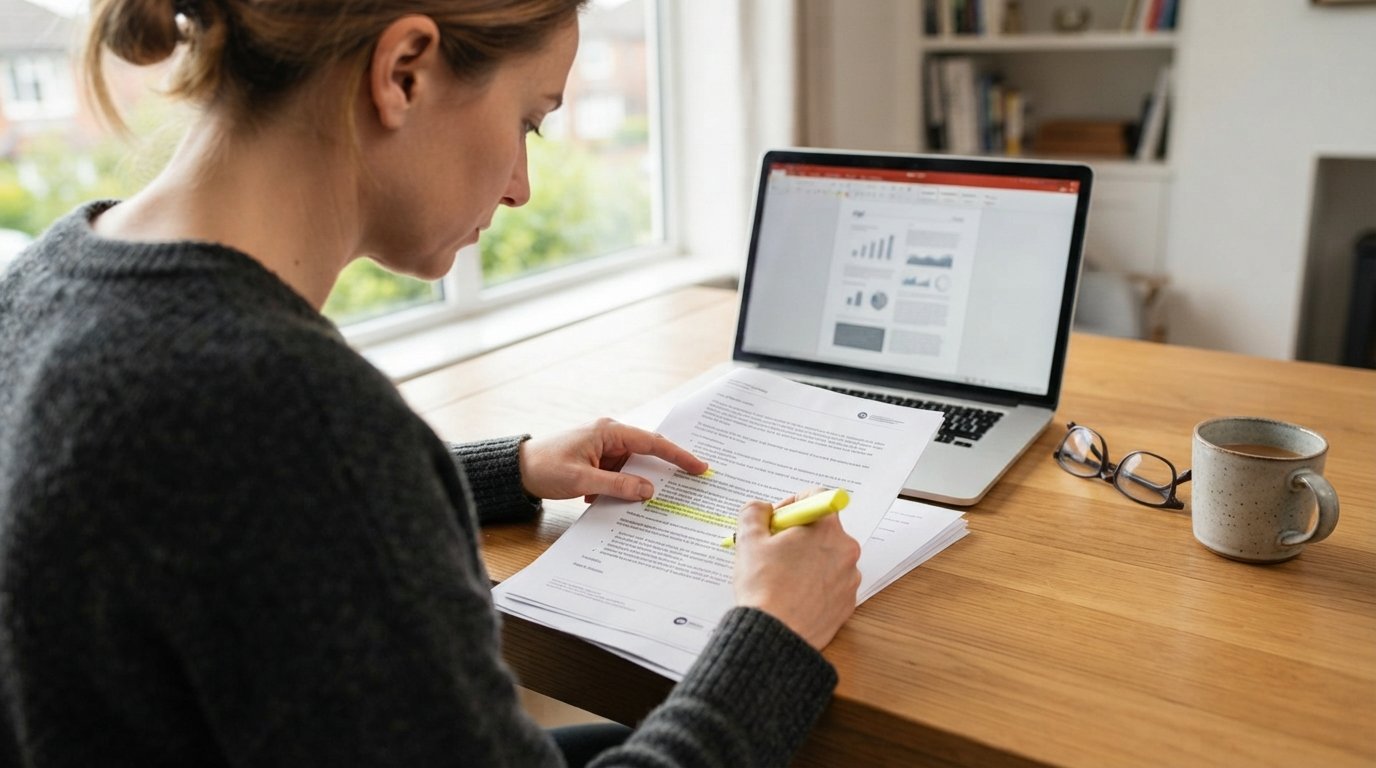
Reading a policy document in Amazon is no different from reading a paper copy, but there are some digital tricks that can make it easier. First, use the search function in your PDF reader to find key terms like "exclusion," "deductible," or "limits." This can quickly take you to the relevant sections. Second, highlight important passages and add comments so you can review them later. Third, consider storing your policy in a dedicated folder in Amazon Drive and naming it with the effective dates for easy retrieval.
If you prefer a more structured approach, create a one-page summary of your policy that includes the coverage types, limits, deductibles, and key exclusions. This summary becomes your quick reference guide. You can also share it with family members who drive your car, so everyone understands the coverage. And if you ever have questions, do not hesitate to call your insurer or a licensed agent. They can explain confusing terms and help you make informed decisions.
For those who also need life insurance, consider exploring term life insurance options through TermLifePlan, where licensed agents can help you find coverage that fits your budget. While auto insurance protects your vehicle, life insurance protects your family's financial future, and both are important pieces of a comprehensive financial plan.
Common Pitfalls to Avoid When Reading Your Policy
Even with a careful reading, it is easy to fall into common traps. One pitfall is assuming that because a coverage is listed, it automatically applies to every situation. Always read the exclusions and conditions to see if there are limitations. Another pitfall is ignoring the definitions section. Terms like "insured" may not include all drivers in your household, so check who is covered. A third pitfall is overlooking the importance of endorsements. If you added an endorsement, make sure it is listed on the declarations page and that you understand its terms.
Another common mistake is not reviewing the policy after a life change. If you get married, buy a new car, or move to a new state, your policy may need updates. Reading your policy periodically helps you keep it current. Finally, do not assume that the cheapest policy is the best. Low premiums often come with high deductibles or low limits, which can cost you more in the long run. Balance cost with coverage to make a wise choice.
If you are also shopping for health insurance, remember that NewHealthInsurance.com offers real-time quotes and educational resources to help you compare plans. Their licensed agents can guide you through the process and help you find affordable coverage. Whether you need auto, health, or life insurance, taking the time to read and understand your policy is a smart investment in your financial well-being.
Reading your car insurance policy document in Amazon does not have to be a daunting task. By breaking it down into sections and focusing on the key information, you can gain a clear understanding of your coverage and make confident decisions. Start with the declarations page, review the coverage and exclusions, decode the definitions, and check endorsements. With practice, you will become proficient at navigating even the most complex policy documents. And remember, if you need help with health insurance, NewHealthInsurance.com is here to assist you with quotes and enrollment support.
Compare health plans
Finding plans in your area…