How to Read a Health Insurance Formulary Drug Tier List
Master how to read a health insurance formulary drug tier list to predict prescription costs, avoid surprise pharmacy bills, and find affordable alternatives.
By Dana Whitaker
Compare health plans
Finding plans in your area…
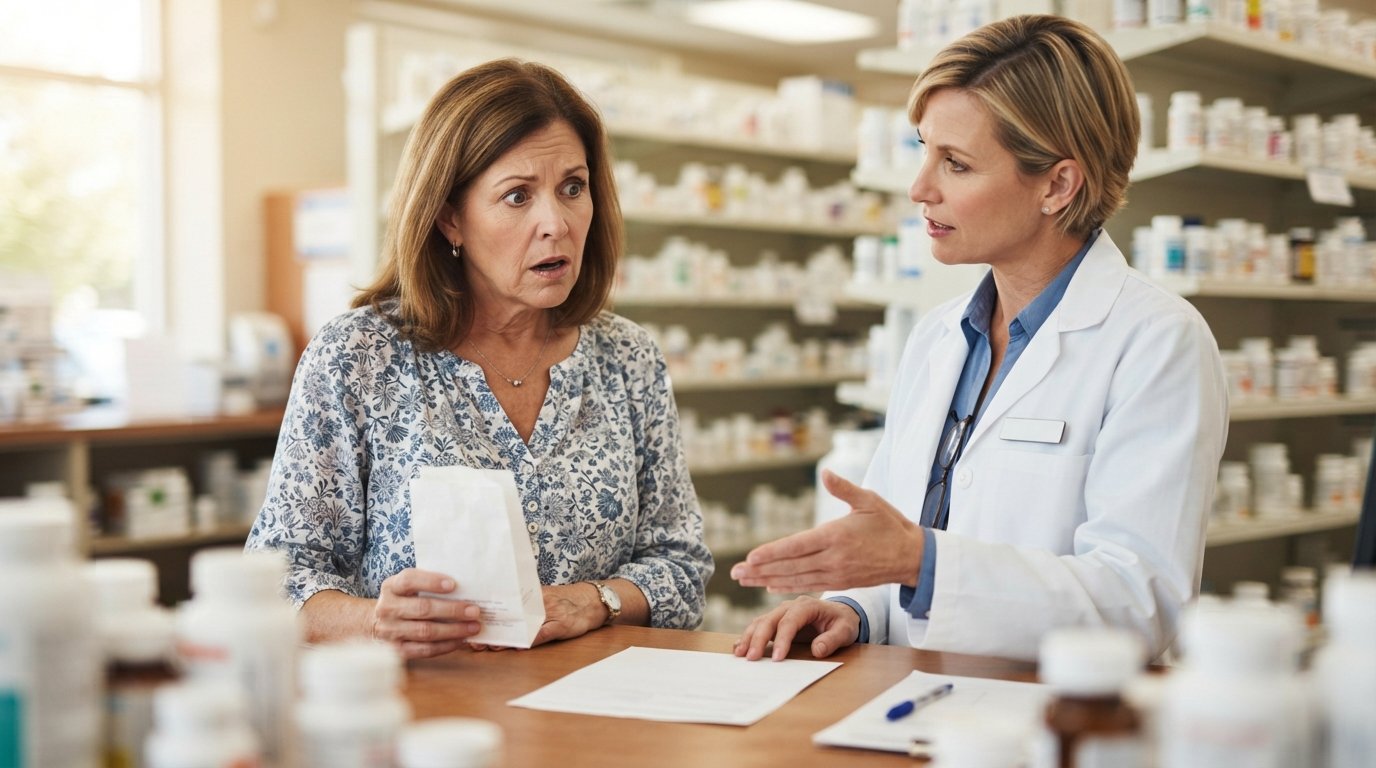
Your doctor just prescribed a medication, and you are standing at the pharmacy counter. The pharmacist tells you the cost is $340, but you expected a $15 copay. What happened? The answer is almost certainly in your health plan's formulary drug tier list. Understanding this document is one of the most practical skills you can develop as a health insurance consumer, and it directly affects how much you pay for prescriptions every month. Whether you have an ACA Marketplace plan, an employer-sponsored plan, or a Medicare Part D plan, the tier structure determines your financial responsibility. This guide walks you through exactly how to read a health insurance formulary drug tier list so you can predict costs, avoid surprise bills, and work with your doctor to find affordable alternatives.
What Is a Formulary and Why Does It Matter?
A formulary is simply the list of prescription drugs your health insurance plan agrees to cover. It is not a random collection. Insurance companies build formularies using a committee of doctors and pharmacists who evaluate each drug's effectiveness, safety, and cost. The formulary is then organized into tiers, which are cost-sharing categories. Each tier has its own copay or coinsurance amount, and the higher the tier number, the more you typically pay out of pocket.
The formulary matters because it is a contract between you and your insurer. If a drug is on the formulary, the plan covers it according to the tier rules. If a drug is not on the formulary (often called non-formulary or excluded), you may pay the full retail price or need a prior authorization before the plan will cover any portion. This is where many people get caught off guard. They assume their plan covers everything their doctor prescribes, but that is not how formularies work. The tier placement is the key that unlocks your actual cost.
Formularies change every year, usually on January 1. A drug that was Tier 1 last year might move to Tier 3 this year, which means your copay could jump from $10 to $75. Insurers must notify you of changes before the plan year begins, but those notices are often buried in enrollment materials. Knowing how to find and read your formulary gives you control over your prescription budget.
Understanding the Tier Structure: From Generic to Specialty
Tiers are the backbone of any formulary. While the exact number of tiers varies by plan, most health insurance formularies use four to five tiers. The logic is straightforward: lower tiers contain cheaper drugs, and higher tiers contain more expensive or specialized drugs. Your share of the cost increases as you move up the tiers.
Here is a typical tier structure you might see in an ACA Marketplace plan or employer plan:
- Tier 1 (Preferred Generics): These are generic drugs with the lowest copays, often $5 to $15. They are the most cost-effective options and are usually the first line of treatment for common conditions.
- Tier 2 (Preferred Brand-Name Drugs): These are brand-name medications that the plan has negotiated a discount for. Copays might range from $30 to $60.
- Tier 3 (Non-Preferred Brand-Name Drugs): These are brand-name drugs that have cheaper alternatives on lower tiers. Copays can be $75 to $150 or more.
- Tier 4 (Specialty Drugs): These are high-cost medications, often biologics or drugs for complex conditions like cancer, multiple sclerosis, or rheumatoid arthritis. You may pay coinsurance (a percentage of the drug cost) rather than a flat copay, often 20% to 40%.
- Tier 5 (Premium Specialty or Not Covered): Some plans have a fifth tier for the most expensive drugs or for drugs that are not covered at all. You may pay the highest coinsurance or the full price.
The critical takeaway is that tier placement is not a judgment on whether a drug is "good" or "bad." It is a pricing decision. A Tier 3 drug might be the perfect medication for you, but your plan wants to steer you toward a Tier 1 or Tier 2 alternative first. If your doctor prescribes a Tier 3 drug, you can ask whether a Tier 1 or Tier 2 option would work just as well. Often, there is a generic equivalent or a therapeutic alternative that costs far less.
It is also important to note that Medicare Part D formularies follow a similar tier structure but have specific rules. For example, Medicare Part D plans must cover at least two drugs in each therapeutic category, and they cannot exclude drugs covered by Medicare Part A or B. If you are navigating Medicare and prescription drug coverage, resources like NewMedicare provide detailed explanations of Part D tiers and how they interact with your overall Medicare benefits.
How to Find Your Plan's Formulary Drug Tier List
Before you can read a tier list, you need to find it. Every health insurance plan is required to make its formulary available to members. The challenge is knowing where to look. Here are the most reliable places to find your plan's formulary:
- Your plan's member portal: Log into your health insurance account online. Most insurers have a "Pharmacy" or "Prescription Drug" section where you can download the formulary as a PDF or search for a specific drug.
- Your plan's website: Even without logging in, you can usually find the formulary under a "Members" or "Resources" tab. Look for a link titled "Formulary," "Drug List," or "Prescription Drug Coverage."
- Your Summary of Benefits and Coverage (SBC): This standardized document, which you receive when you enroll, includes a summary of your prescription drug coverage but not the full formulary. It will tell you how many tiers your plan has and what the cost-sharing looks like for each.
- Your employer's HR department: If you have employer-sponsored insurance, HR can provide the formulary or direct you to the insurer's portal.
- Customer service: Call the member services number on your insurance card. They can mail or email you a copy of the formulary.
Once you have the formulary document, do not be intimidated by its length. It is usually a searchable PDF. Use the "Find" function (Ctrl+F or Command+F) to search for your specific medication by its generic or brand name. The formulary will list the drug alphabetically and indicate its tier. Some formularies also include prior authorization requirements, quantity limits, or step therapy protocols next to each drug, which we will cover next.
If you are comparing plans during Open Enrollment or a Special Enrollment Period, you can usually find each plan's formulary on the insurer's website before you enroll. This is a smart step to take if you or a family member takes a costly medication. A plan with a low premium might have a formulary that places your drug on a high tier, making the total annual cost higher than a plan with a slightly higher premium but better drug coverage.
Reading the Fine Print: Prior Authorization, Step Therapy, and Quantity Limits
Tier placement is not the only factor that determines your access to a medication. Formularies often include utilization management tools that add layers of requirements before a drug is covered. These tools are designed to control costs and ensure drugs are used appropriately, but they can also create barriers for patients.
Here are the three most common utilization management tools you will see on a formulary:
- Prior Authorization (PA): This means your doctor must submit clinical information to the insurance company, and the plan must approve the drug before it will cover it. Without prior authorization, the pharmacy may not fill the prescription, or you may pay the full cash price. The prior authorization process can take days or weeks, so it is important to start early if you know you will need a medication that requires it.
- Step Therapy: Also called "fail first," this requires you to try a lower-tier or preferred drug before the plan will cover a higher-tier alternative. If the first drug does not work or causes side effects, your doctor can document that and request approval for the next step. Step therapy can be frustrating, but it is a common feature in both commercial and Medicare Part D formularies.
- Quantity Limits: The plan may limit how much of a drug you can receive per month. For example, a plan might cover only 30 tablets per month of a certain medication. If your doctor prescribes 60, you may need a prior authorization for the higher quantity.
These requirements are usually listed in the formulary next to the drug name, often with abbreviations like "PA," "ST," or "QL." Some formularies include a key or legend at the beginning to explain the abbreviations. If you see these codes next to your medication, it does not mean the drug is denied. It means there are extra steps. Your doctor's office is likely familiar with these requirements and can help you navigate them.
If you encounter a prior authorization denial or a step therapy requirement that seems unreasonable, you have rights. You can appeal the decision, and your doctor can provide a letter of medical necessity explaining why the requested drug is the right choice for you. The appeal process is outlined in your plan documents, and you can also seek help from a patient advocacy organization or your state's insurance department.
What to Do When Your Drug Is Not on the Formulary
Discovering that your medication is not on your plan's formulary can be alarming, especially if you have been taking it successfully for years. But a non-formulary status does not always mean you are out of options. There are several paths you can take.
First, ask your doctor if there is a formulary alternative. Many drugs have generic equivalents, therapeutic alternatives in the same drug class, or over-the-counter options that could work. Your doctor can review your formulary and suggest a covered alternative. This is often the fastest and least expensive solution.
Second, you can request a formulary exception. This is a formal request to your insurance plan to cover a non-formulary drug as if it were on a lower tier. Your doctor must provide clinical justification, such as documentation that formulary alternatives are ineffective or cause harmful side effects. If the exception is approved, you pay the cost-sharing amount for the tier you requested. Formulary exceptions are not guaranteed, but they are a legitimate and commonly used process.
Third, you can pay out of pocket for the non-formulary drug, sometimes using a discount card or manufacturer coupon. This may be a temporary solution while you pursue an exception or appeal. However, be aware that payments for non-formulary drugs typically do not count toward your deductible or out-of-pocket maximum, so your overall costs could be higher.
Fourth, if you are enrolled in a plan through the ACA Marketplace and your drug is not covered, you may be able to switch plans during Open Enrollment or a Special Enrollment Period. If you have double coverage through two plans, which is sometimes possible through a spouse's employer, you may be able to use the other plan's formulary. Our guide to double coverage health insurance explains how coordinating benefits between two plans can help you access medications that one plan does not cover.
Finally, if you are on Medicare, you can switch Part D plans during the annual Open Enrollment Period (October 15 to December 7) or during a Special Enrollment Period if you qualify. Before switching, always check the new plan's formulary to make sure your medications are covered at a tier you can afford.
Practical Tips for Managing Your Prescription Costs
Understanding your formulary is the first step, but proactive management can save you even more. Here are some practical strategies to keep your prescription costs down:
- Review your formulary every year: Formularies change annually. Take 15 minutes during Open Enrollment to check whether your medications have moved to a different tier or been removed from the formulary.
- Ask about generic alternatives: Generic drugs are chemically equivalent to brand-name drugs and are almost always on a lower tier. If your doctor prescribes a brand-name drug, ask if a generic is available.
- Use mail-order pharmacies: Many plans offer a 90-day supply through mail order at a lower cost than three separate 30-day retail copays.
- Check for manufacturer assistance programs: Many drug manufacturers offer copay assistance or patient assistance programs for high-cost medications. These can reduce your out-of-pocket costs, though restrictions apply for Medicare and Medicaid beneficiaries.
- Coordinate with your doctor: Bring your formulary to your appointment. Your doctor can see which drugs are covered and at what tier, making it easier to prescribe a medication you can afford.
If you are shopping for a new health insurance plan and want to compare formularies across carriers, working with a licensed broker can simplify the process. NewHealthInsurance.com helps individuals and families compare ACA Marketplace plans, Medicare options, and short-term coverage across all 50 states. You can enter your zip code, complete a short form, and review matched plans in less than five minutes. If you need personalized help understanding how a plan's formulary affects your specific medications, call (833) 864-8035 to speak with a licensed insurance expert.
Reading a formulary drug tier list is not just about understanding insurance jargon. It is about taking control of your health care budget and ensuring you can afford the medications you need. The more familiar you become with your plan's tier structure, the better equipped you will be to advocate for yourself, ask the right questions, and avoid the shock of an unexpected pharmacy bill. Start by downloading your plan's formulary today and searching for each of your prescriptions. A few minutes of research can save you hundreds of dollars over the course of a year.
Compare health plans
Finding plans in your area…