How to Find a Dentist That Accepts Medicaid or Marketplace Dental
Find a dentist who takes Medicaid or Marketplace dental with our practical guide. Call (833)-864-8035 for help comparing dental coverage options.
By Marissa Bloom
Compare health plans
Finding plans in your area…
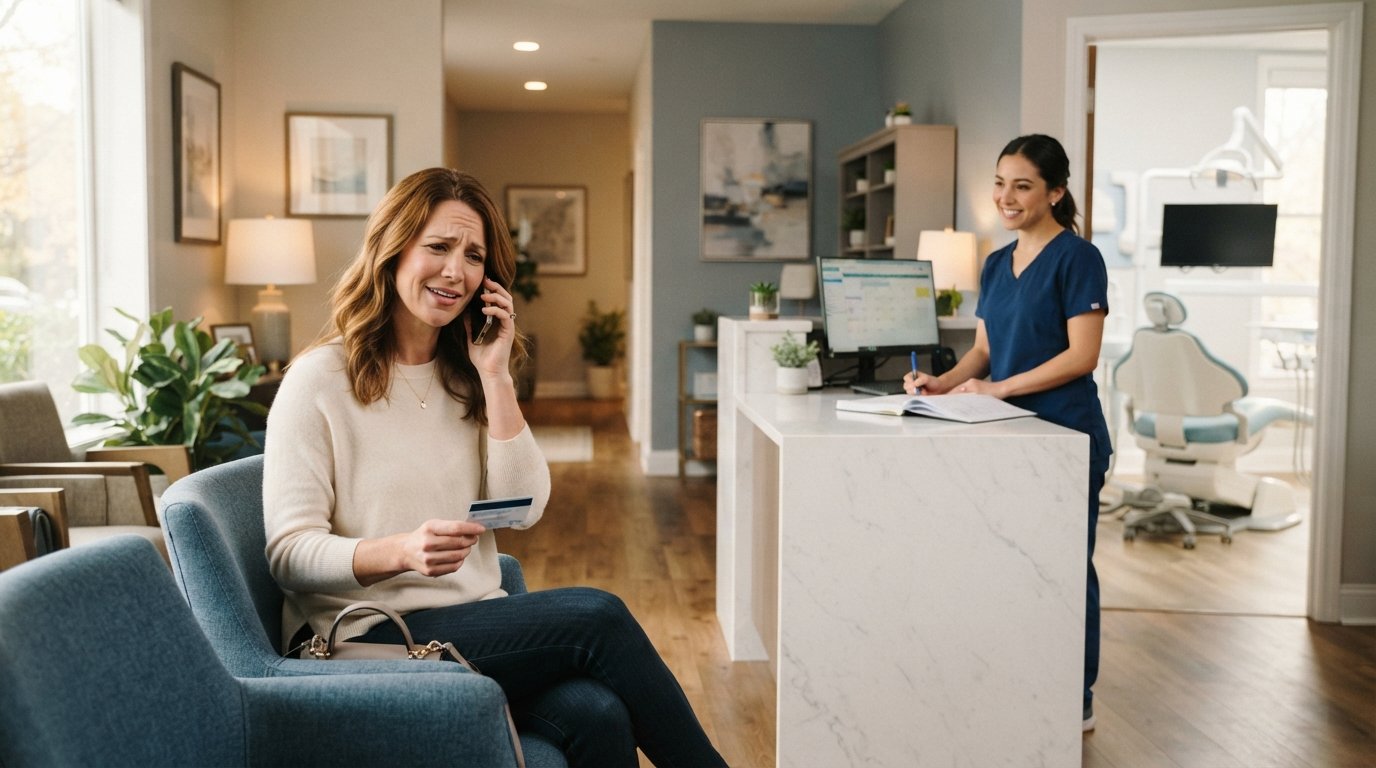
Finding a dentist who accepts your Medicaid or Marketplace dental plan can feel like searching for a needle in a haystack, especially when you are in pain or facing a looming deadline. You call office after office, only to hear "we don't take that plan" or "we're not accepting new patients right now." The frustration is real, and the stakes are high: untreated dental issues can spiral into costly ER visits, lost workdays, and serious health complications. But here is the good news: with the right strategy, you can locate a provider who works with your coverage, and you do not have to navigate the maze alone.
This guide walks you through exactly how to find a dentist that accepts Medicaid or marketplace dental plans, from understanding what your plan actually covers to using the right search tools and knowing your options when the first few calls do not pan out. Whether you are on Medicaid, have an ACA Marketplace plan with a pediatric or adult dental rider, or are simply trying to make sense of your benefits before your next cleaning, the steps below will save you time and help you avoid surprise bills.
Understand What Dental Coverage You Actually Have
Before you start calling dental offices, you need a clear picture of your dental benefits. Medicaid and Marketplace plans handle dental coverage very differently, and even within the same program, the rules can vary dramatically depending on your state and the specific plan you chose. Knowing these details upfront prevents wasted calls and helps you ask the right questions when you do reach a provider.
Medicaid dental coverage is not guaranteed for adults in every state. While children enrolled in Medicaid are entitled to comprehensive dental services through the Early and Periodic Screening, Diagnostic, and Treatment (EPSDT) benefit, adult dental benefits are optional for states. As of recent years, a majority of states offer some level of adult dental coverage, but the scope ranges from emergency-only care (like tooth extractions) to preventive services like cleanings and X-rays, to full restorative work including crowns and dentures. Some states impose annual spending caps, limit the number of procedures per year, or require prior authorization for major work. If you are on Medicaid, your first stop should be your state's Medicaid agency website or your managed care plan's member handbook to confirm what dental services are covered for adults.
Marketplace dental coverage is similarly nuanced. Under the Affordable Care Act, pediatric dental care is considered an essential health benefit, so most Marketplace plans include dental coverage for children under 19. Adult dental, however, is not an essential benefit. Some Marketplace plans bundle adult dental into the medical plan, while others offer it as a separate stand-alone dental plan (SADP) that you must purchase alongside your medical policy. Stand-alone dental plans typically follow a tiered structure: preventive care (cleanings, exams) may be covered at 100% with no waiting period, while basic services (fillings) and major services (crowns, root canals) come with coinsurance, deductibles, and annual maximums, often around $1,000 to $1,500 per person.
Gather these specifics before you search:
- Plan type and network: Is your dental coverage through a Medicaid managed care organization (like a specific MCO), a Marketplace medical plan with embedded dental, or a stand-alone dental plan? Each has its own network of contracted dentists.
- Covered services and limits: Note which procedures are covered, any annual maximum, waiting periods for major services, and whether pre-authorization is required.
- Cost-sharing: Understand your copays, coinsurance percentages, and deductible so you can estimate out-of-pocket costs before scheduling.
- Referral rules: Some plans require a referral from a primary care provider or a gatekeeper before you can see a specialist like an oral surgeon.
Having this information in hand not only makes your search more efficient but also signals to dental office staff that you are an informed patient, which can smooth the scheduling process. If you are unsure which plan you have or want to compare dental coverage options for next year, our guide on how to find cheap Marketplace insurance plans USA can help you evaluate affordable medical and dental combinations.
Use the Right Search Tools to Find In-Network Dentists
Once you know your plan details, the next step is to use the search tools that your insurer and state provide. These directories are the most reliable way to find dentists who are contractually obligated to accept your coverage, though they are not always perfectly accurate. Plan to verify by phone before booking an appointment.
Start with your insurer's online provider directory. Every Medicaid managed care plan and every Marketplace dental plan maintains a searchable directory of in-network providers. Log in to your member portal or visit the plan's website and use the "Find a Dentist" or "Provider Search" tool. Filter by your plan type, location, and the services you need (for example, pediatric dentistry, oral surgery, or general dentistry). The directory should indicate whether the dentist is accepting new patients, though this information can be outdated, so a phone call is still essential.
Check your state Medicaid agency's resources. Many state Medicaid programs publish their own dentist locator tools or PDF directories. For example, some states offer an online "Find a Dentist" map that lets you search by county and filter for providers who accept adult Medicaid or specific managed care plans. State dental association websites sometimes also maintain lists of Medicaid-participating dentists, though these are less common.
Use community health center locators. Federally Qualified Health Centers (FQHCs) and look-alike clinics often provide dental services on a sliding fee scale and frequently accept Medicaid. The Health Resources and Services Administration (HRSA) operates a Find a Health Center tool that lets you search by address and filter for dental services. These centers are a lifeline for patients who cannot find a private-practice dentist willing to take their coverage.
When you call a dental office, be specific and prepared. Ask these questions:
- Are you currently accepting new patients with [your specific plan name]?
- Is [dentist's name] an in-network provider for my plan?
- Do you require a referral or pre-authorization for the service I need?
- What will my out-of-pocket cost be for a cleaning, exam, and any X-rays?
- How long is the wait for a new patient appointment?
Document the name of the person you speak with and the date of the call. If you later receive a bill that contradicts what you were told, having a record can help you dispute charges with your insurer. For broader help comparing dental and medical plan options, you can also visit InsuranceShopping.com, a comprehensive resource for understanding and comparing insurance policies, including health and dental coverage.
Find Sliding-Scale and Community Dental Clinics
If your Medicaid plan has limited dental benefits or you cannot find an in-network dentist nearby, sliding-scale clinics and community health centers are an excellent alternative. These organizations receive federal or state funding to provide care to underserved populations and typically charge based on your income, often using a sliding fee scale that can reduce costs to a nominal amount.
Federally Qualified Health Centers (FQHCs) are community-based organizations that provide primary care, dental, and behavioral health services regardless of ability to pay. They accept Medicaid and Medicare and offer sliding-scale fees for uninsured or underinsured patients. You can locate an FQHC near you using the HRSA Find a Health Center tool mentioned earlier. Many FQHCs have dental departments with hygienists and dentists on staff, though wait times for non-emergency appointments can be long.
Dental schools and residency programs are another underused resource. Dental schools often operate clinics where supervised students provide low-cost care, including cleanings, fillings, and more complex procedures. While appointments may take longer and be scheduled around academic calendars, the savings can be significant. Search for dental schools in your state and ask about their community clinic hours and fees.
Nonprofit and charity dental clinics exist in many communities, often run by organizations like Mission of Mercy, Remote Area Medical (RAM), or local faith-based groups. These clinics may offer free or low-cost care on specific days or through periodic events. Community health centers, United Way chapters, and your local health department can often point you toward these resources. When calling, ask about eligibility requirements, what services are available, and whether they accept your Medicaid or Marketplace plan.
Sliding-scale clinics are not a permanent substitute for a dental home, but they can bridge the gap while you search for a long-term provider or save up for a needed procedure. They also often provide preventive care that can prevent small issues from becoming expensive emergencies.
What to Do If You Need Urgent Dental Care Without Coverage
Dental emergencies do not wait for open enrollment or a prior authorization to clear. If you are in pain, have swelling, or have suffered a dental injury, you need care quickly, even if your coverage is limited or nonexistent. Here is how to navigate urgent situations without derailing your finances.
Call your Medicaid or Marketplace plan's nurse line or member services first. Many plans offer 24/7 nurse advice lines that can help you determine whether your situation is a true emergency and direct you to in-network urgent care or dental providers. Some plans also have arrangements with urgent dental clinics that offer after-hours care. If you are on Medicaid, ask whether emergency dental services are covered (they often are, even in states with limited adult benefits, because emergency care is frequently mandated).
Seek care at a dental school or community clinic with urgent care hours. Many FQHCs and dental schools reserve slots for urgent needs. Call ahead to explain your situation and ask about same-day availability. If you cannot get through, consider visiting a hospital emergency department for severe swelling, fever, or trauma, though be aware that ERs typically provide pain management and antibiotics rather than definitive dental treatment.
Explore dental discount plans and membership programs. If you are uninsured or underinsured, a dental discount plan (not insurance) can reduce the cost of procedures by 10% to 60% in exchange for an annual membership fee. These plans are not a substitute for comprehensive coverage, but they can make urgent care more affordable. Compare the annual fee against the savings on the specific procedure you need before enrolling.
Ask about payment plans and financial assistance. Many private dental offices offer internal payment plans or partner with third-party financing companies like CareCredit. Nonprofit clinics may have charitable funds to cover urgent care for low-income patients. Do not assume you cannot afford care; ask directly about financial assistance options.
Prevention is always cheaper than treatment, so once the urgent issue is resolved, prioritize finding a dental home for regular cleanings and checkups. If you are shopping for coverage that includes dental benefits, NewHealthInsurance.com can help you compare Marketplace plans that offer pediatric dental coverage or stand-alone dental plans for adults. Their licensed agents can walk you through plan options in your state and help you understand which dental networks are included. You can reach their team at (833)-864-8035 for personalized assistance.
Build a Long-Term Dental Home and Advocate for Your Coverage
Finding a dentist who accepts your coverage is not a one-time task; it is the beginning of an ongoing relationship that protects your oral health and your wallet. Once you locate a provider, take steps to confirm your benefits annually, especially if you change plans during open enrollment or experience a qualifying life event. Dental networks change, and a dentist who accepted your plan last year may no longer be in-network this year.
At your first visit, bring your insurance card and a list of questions about coverage, costs, and treatment recommendations. Ask the front desk to verify your benefits before services are rendered and to provide a written estimate for any non-preventive work. Keep copies of explanation of benefits (EOB) statements and compare them to what you were told. If you notice discrepancies, contact your insurer and the dental office promptly to resolve them.
If you are unable to find an in-network dentist or your plan's network is inadequate, you have options. You can file a grievance with your Medicaid managed care plan or Marketplace insurer, request a network adequacy review, or ask for a single-case agreement that allows you to see an out-of-network dentist at in-network rates if no in-network provider is available. State insurance departments and Medicaid ombudsman offices can help you navigate appeals. For more guidance on maximizing your health insurance benefits and understanding your rights, the experts at NewHealthInsurance.com are a valuable resource.
Finally, remember that dental coverage is part of your overall health strategy. Untreated dental disease is linked to heart disease, diabetes complications, and pregnancy risks. Investing time in finding a dentist who accepts your Medicaid or Marketplace plan is an investment in your long-term well-being. With the tools and steps outlined here, you can navigate the system confidently and get the care you deserve.
Compare health plans
Finding plans in your area…