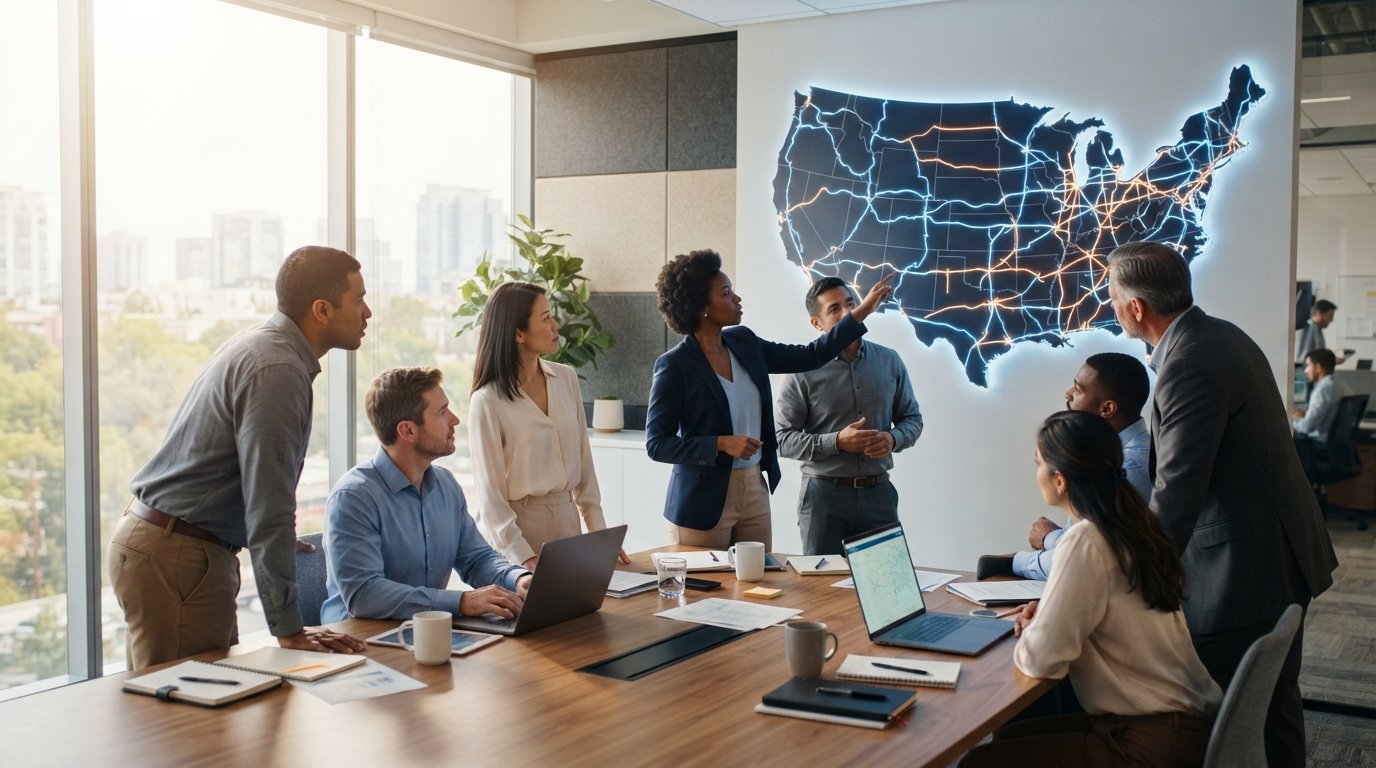
Health Insurance Nationwide Multi-State Coverage Guide
Health insurance nationwide multi-state coverage keeps you protected when you live, work, or travel across state lines. Compare plans and avoid gaps in care.
By Nathaniel Crowley
Compare health plans
Finding plans in your area…
Moving to a new state, managing a business with employees scattered across the country, or simply traveling for months at a time can turn health insurance into a confusing puzzle. Your current plan may have worked perfectly in your old zip code, but once you cross state lines, the rules, networks, and available plans can change dramatically. Understanding health insurance nationwide multi-state coverage is the key to avoiding surprise medical bills and gaps in care. This guide breaks down how multi-state plans work, who needs them, and how to find the right coverage for your situation.
What Is Health Insurance Nationwide Multi-State Coverage?
Health insurance nationwide multi-state coverage refers to health plans designed to provide benefits across more than one state. Most traditional health insurance plans, including those sold on the ACA Marketplace, are state-specific. They are built around provider networks that operate within a single state. If you receive care outside that network or outside that state, you may pay significantly more or receive no coverage at all, except in emergencies.
Multi-state coverage solves this problem by contracting with providers in multiple states or by using a national network. These plans are common in the employer-sponsored market, especially for large companies with offices in different locations. They are also available to individuals and families in certain situations, such as students, frequent travelers, and remote workers. The goal is to ensure you can access in-network care no matter where you are.
However, not all multi-state plans are created equal. Some offer full nationwide networks, while others provide coverage only in select states. Some use a primary state network with limited out-of-state benefits. Understanding the difference is critical before you enroll. If you are comparing double coverage options or need to coordinate benefits between two plans, our guide on double coverage health insurance pros and cons explains how secondary policies interact with primary coverage.
How Multi-State Health Insurance Plans Work
Multi-state plans typically fall into two categories: national networks and state-specific networks with reciprocal agreements. National networks, such as those offered by large carriers like Cigna, Aetna, or Anthem, have contracted providers in all 50 states. When you enroll in a plan with a national network, you can see any in-network provider regardless of your location. This is the most seamless form of multi-state coverage.
State-specific networks with reciprocal agreements are more common in regional plans. For example, a plan in Texas might have an agreement with a carrier in Oklahoma, allowing you to receive in-network care in both states. These agreements are often limited to neighboring states or specific metropolitan areas. They are less flexible than national networks but can be more affordable.
Another model is the HMO or EPO with a nationwide affiliate network. These plans may require you to designate a primary care physician in your home state, but they allow you to access care through affiliated providers when you travel. However, you may need a referral or prior authorization for non-emergency care outside your home state. Always check the plan's provider directory for the states you frequent.
Here are the key factors that determine how a multi-state plan works:
- Network type: PPO and POS plans are more likely to offer nationwide coverage than HMOs or EPOs.
- Carrier size: Large national carriers are more likely to have broad networks across states.
- Plan design: Some plans explicitly include multi-state coverage, while others limit it to emergencies only.
- State regulations: Insurance rules vary by state, and some states require carriers to offer reciprocal access.
Even with a national network, you may still face higher costs for out-of-state care. Some plans apply a separate deductible or coinsurance for services received outside your home state. Others require prior authorization for non-emergency procedures. Reading the plan's summary of benefits and coverage carefully is essential.
Who Needs Nationwide Multi-State Coverage?
Multi-state coverage is not necessary for everyone, but it is critical for certain groups. If you fall into any of the following categories, you should prioritize plans with broad geographic coverage.
First, remote workers and digital nomads who travel frequently or live in multiple states throughout the year need coverage that follows them. A plan that only works in one state could leave you with thousands of dollars in out-of-network bills if you get sick while traveling. Second, small business owners with employees in multiple states must offer a plan that provides in-network access for all staff, regardless of location.
Third, students attending college out of state often need coverage that works both at school and at home. While many universities offer student health plans, they may not provide nationwide coverage. Fourth, families with children in different states, such as a child attending college or a parent living in another state, need a plan that covers everyone. Finally, frequent travelers and snowbirds who spend months in different states each year should consider multi-state coverage to avoid gaps.
If you are shopping for coverage during Open Enrollment or a Special Enrollment Period, NewHealthInsurance.com can help you compare plans that offer multi-state networks. Their platform allows you to enter your zip code, complete a short form, and compare matched plans in less than five minutes. You can also call their primary helpline at (833) 864-8035 for personalized assistance.
Challenges and Limitations of Multi-State Coverage
While multi-state coverage sounds ideal, it comes with trade-offs. The most significant challenge is cost. Plans with nationwide networks often have higher premiums than state-specific plans because the carrier must maintain a larger provider network. You may also face higher deductibles or copays for out-of-state care.
Another limitation is provider availability. Even if a plan advertises nationwide coverage, the network may be narrow in certain states. For example, a plan might have excellent coverage in California and New York but limited providers in Montana or Wyoming. Always check the provider directory for the specific states and cities you will be in.
Prior authorization requirements can also complicate multi-state care. Many plans require you to obtain prior authorization before receiving non-emergency services outside your home state. This process can be time-consuming and may delay care. If you need help navigating prior authorization, NewHealthInsurance.com offers resources and guidance to help you understand the process.
Finally, multi-state coverage is not always available to individual buyers. Many ACA Marketplace plans are state-specific, and you may need to enroll in a plan through your employer or a private carrier to get nationwide coverage. If you are self-employed or buy insurance on your own, you may have fewer options.
How to Find the Right Multi-State Plan
Finding the right multi-state plan requires research and comparison. Start by identifying the states where you need coverage. If you live in one state but travel frequently to another, focus on plans that have strong networks in both. If you have employees in multiple states, look for carriers with national networks.
Next, review the plan's provider directory. Do not rely on marketing materials alone. Check that your doctors and hospitals are in-network in every state you need. You can usually find this information on the carrier's website or by calling their customer service.
Then, compare costs. Look at premiums, deductibles, copays, and coinsurance for both in-state and out-of-state care. Some plans charge higher cost-sharing for out-of-network or out-of-state services, so factor that into your budget. Also, check whether the plan requires prior authorization for out-of-state care.
Finally, consider working with a broker or licensed agent. NewHealthInsurance.com is a licensed health insurance brokerage that connects you with plans from carriers like Humana, Cigna, Anthem, Kaiser Permanente, Aetna, Coventry Health Care, and Ambetter Health. Their experts can help you compare options and enroll in a plan that meets your multi-state needs. You can reach their quote and enrollment support team at (833) 864-8115.
For those who are also navigating Medicare, NewMedicare is a privately operated educational resource and service platform that helps individuals understand, compare, and enroll in Medicare plans. It serves people approaching age 65, current beneficiaries, caregivers, and those with disabilities who are eligible for Medicare. The site offers unbiased information on Medicare Parts A, B, C, D, and Medigap, along with personalized plan comparisons. If you are eligible for Medicare and need coverage that works across states, NewMedicare can help you explore your options.
Multi-State Coverage for Small Businesses
Small businesses with employees in multiple states face unique challenges. Offering health insurance that works for everyone can be difficult, especially if your workforce is spread across the country. However, there are options available.
One option is to work with a national carrier that offers small group plans with multi-state networks. Carriers like Cigna, Aetna, and Anthem offer group plans that can cover employees in multiple states. These plans typically use a national network, so employees can access in-network care wherever they live.
Another option is to use a professional employer organization (PEO) or a staffing agency that offers benefits. PEOs can provide access to large-group plans with nationwide networks, even for small businesses. However, PEOs charge fees and may require you to transfer some HR responsibilities.
If you are a small business owner looking for multi-state coverage, NewHealthInsurance.com can help. They offer small business health insurance plans and can connect you with licensed carriers and certified experts. You can start by entering your zip code on their website or calling (833) 864-8035.
Key Takeaways for Choosing Multi-State Coverage
To summarize, here are the most important points to remember when shopping for health insurance nationwide multi-state coverage:
- Check the network: Ensure the plan has in-network providers in every state you need.
- Review costs: Compare premiums and out-of-pocket costs for in-state and out-of-state care.
- Understand prior authorization: Know whether you need approval for non-emergency care outside your home state.
- Consider your situation: Remote workers, students, and small businesses with multi-state employees benefit most from multi-state plans.
- Get help: Work with a broker like NewHealthInsurance.com to compare plans and enroll with confidence.
Multi-state coverage can provide peace of mind and financial protection, but it requires careful planning. By understanding how these plans work and comparing your options, you can find coverage that keeps you and your family protected no matter where you are.
Whether you are moving, expanding your business, or simply want the flexibility to receive care in multiple states, taking the time to research and compare plans is essential. With the right coverage, you can focus on what matters most: your health and your life, without worrying about whether your insurance will follow you across state lines.
Compare health plans
Finding plans in your area…