Health Insurance for Chronic Conditions: Find the Right Plan
Find a plan that covers your specialists and medications without surprise costs. Call (833)-864-8035 for expert help with health insurance for chronic conditions.
Compare health plans
Finding plans in your area…
If you live with diabetes, asthma, rheumatoid arthritis, or another ongoing condition, choosing a health plan is not a generic exercise. The plan that looks cheapest on the sticker price can quietly cost you thousands more over a year through uncovered medications, out-of-network specialists, and surprise prior authorization battles. The right plan is the one that keeps your specific care affordable and accessible, month after month. This guide walks you through how to compare plans with your condition in mind, spot the traps that drive up chronic care costs, and decide when paying a higher premium actually saves you money.
Start With Your Care, Not With the Premium
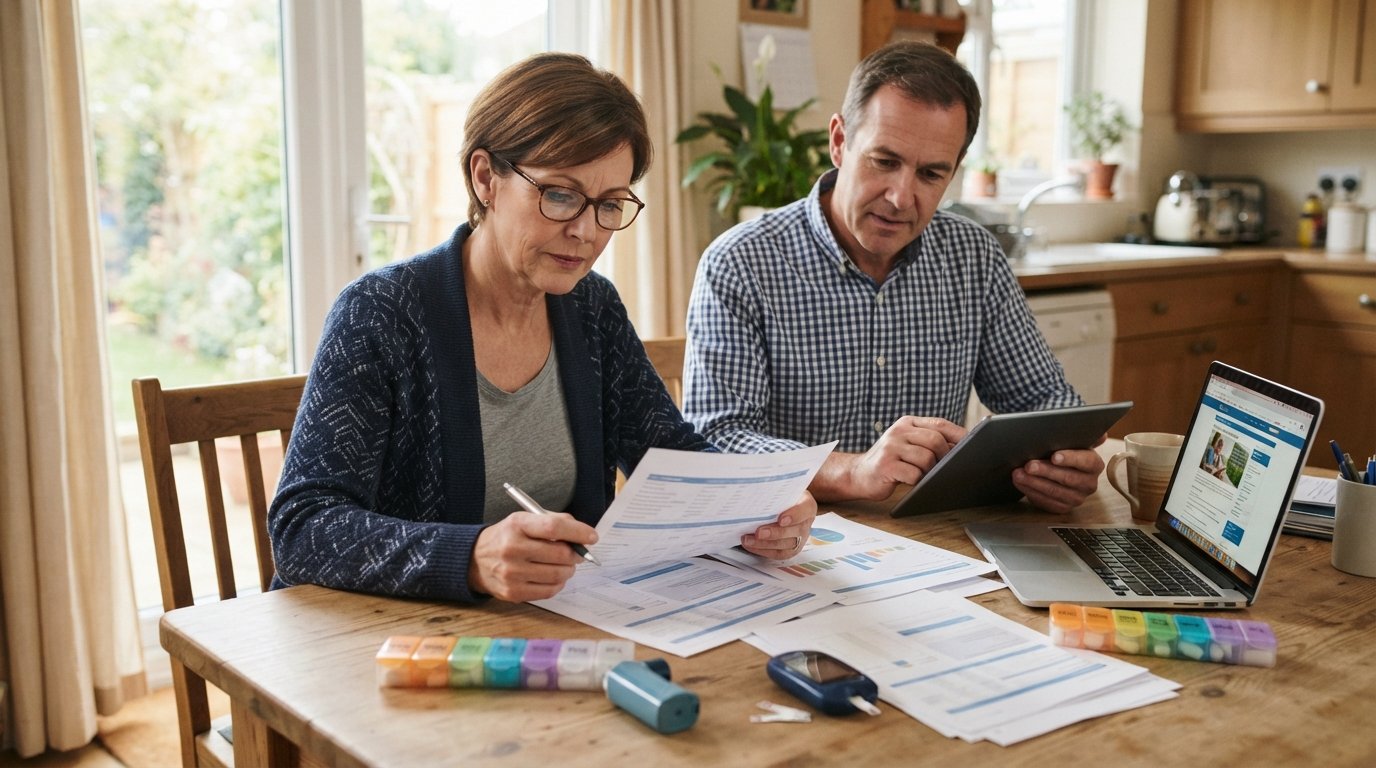
Most people shop for health insurance by sorting plans from lowest to highest premium. For chronic conditions, that approach often backfires. Your premium is only one part of the cost equation, and it is frequently the smallest part when you use care regularly. Before you look at a single price, write down the care you actually use: your specialists, your prescriptions (including exact drug names and doses), your durable medical equipment, and any recurring labs or infusions. That list becomes your checklist for every plan you evaluate.
Once you have that list, you can compare plans on the features that matter most to you. The three levers that drive chronic care costs are the formulary (the plan's drug list), the specialist network, and the cost-sharing structure (copays, coinsurance, deductibles, and out-of-pocket maximums). A plan that wins on one lever can lose badly on another. For example, a plan with a rich specialist network may still exclude the biologic your rheumatologist prescribes, or cover it only after prior authorization.
This is where a broker comparison helps. NewHealthInsurance.com lets you enter your zip code, answer a few questions, and compare ACA Marketplace, Medicare, and short-term plans side by side in under five minutes. You can also call (833) 864-8035 to speak with a licensed agent who can pull plan details specific to your county and your medications. The goal is not to find the cheapest plan but the plan that covers your care with the fewest surprises.
Compare Formularies and Specialist Networks First
The formulary is the single most important document for anyone managing a chronic condition. Every plan publishes a drug list that sorts medications into tiers, and those tiers determine what you pay. A drug that sits on tier 1 might cost you $10 per month, while the same drug on tier 4 could cost hundreds. Worse, some plans exclude certain drugs entirely or require step therapy, meaning you must try a cheaper drug first and fail before the plan covers the one your doctor recommended.
Do not assume your medication is covered just because a plan is sold by a major carrier. Formularies change every year, and the plan you had last year may have moved your drug to a higher tier or added new restrictions. When you compare plans, search each formulary for every drug you take, and note the tier, the copay or coinsurance, and any prior authorization or quantity limit. If you take a specialty drug, such as a biologic for Crohn's disease or a GLP-1 for diabetes, check whether the plan requires you to fill it through a specialty pharmacy and whether that pharmacy is in network.
Specialist networks matter just as much. If your endocrinologist, cardiologist, or rheumatologist is not in the plan's network, you will either pay out-of-network rates or lose continuity of care. Before you enroll, confirm that every provider you see regularly is in network, including any hospital or surgery center they use. Provider directories are often outdated, so call the provider's office and ask which plans they are contracted with for the coming year. A few minutes on the phone can save you from a plan that looks good on paper but forces you to change doctors.
For a deeper look at how coverage works for people who split time between countries or need international care, see our guide on international health insurance USA coverage options. The same principles apply: network and formulary rules determine whether your care is covered.
How Copays and Coinsurance Affect Your Yearly Costs
Chronic care costs add up through frequent small payments, not one big bill. A $40 specialist copay four times a year is $160. A $30 monthly drug copay is $360. Add labs, imaging, and urgent visits, and the totals climb quickly. That is why you need to compare plans using annual cost estimates, not just the premium.
Copays are fixed dollar amounts you pay for a service, such as $25 for a primary care visit or $50 for a specialist. Coinsurance is a percentage you pay after the deductible, such as 20 percent of the allowed amount for an infusion. Plans with low premiums often shift costs to coinsurance, which can be dangerous for chronic care because the allowed amount for specialty drugs and procedures can be very high. A 20 percent coinsurance on a $5,000 biologic is $1,000 per fill until you reach your out-of-pocket maximum.
To compare plans fairly, estimate your total yearly cost by adding the premium for 12 months to your expected copays, coinsurance, and deductible spending. Then cap that estimate at the plan's out-of-pocket maximum, because that is the most you can pay for covered in-network care. The table below shows a simple framework you can use.
- Low premium, high deductible plan: Best if you rarely use care, but risky for chronic conditions because you pay full allowed amounts until the deductible is met.
- Mid-range plan with copays: Predictable costs for office visits and drugs, but check coinsurance for hospital and specialty care.
- High premium, low cost-sharing plan: Higher monthly cost, but lower copays and coinsurance can win if you have frequent visits, expensive drugs, or planned procedures.
Run the math with your actual numbers. A plan that costs $150 more per month but reduces your drug copays by $300 per month is clearly cheaper overall. Conversely, a plan with a low premium can be the better choice if your only care is an annual visit and a generic drug, even with a chronic condition that is well controlled.
Prior Authorization and Referral Rules for Ongoing Treatment
Prior authorization is a process where your insurer must approve certain services or drugs before you receive them. For chronic conditions, prior authorization can become a recurring hurdle. Plans may require reauthorization every few months for ongoing treatments, and a denial can interrupt care while you appeal. Before you enroll, check whether the plan requires prior authorization for your regular treatments, how long approvals last, and whether your specialist's office handles the paperwork.
Referral rules also matter. HMO and POS plans often require a primary care referral before you see a specialist. If you already have a care team you trust, a plan that requires referrals can add friction and delay. PPO plans generally allow you to see specialists without a referral, but they may cost more in premiums. The right choice depends on how much you value direct access versus lower monthly costs.
If you do face a denial, know your rights. ACA plans have appeal processes, and you can request an external review if your internal appeal fails. Keep records of every prior authorization request and approval, and ask your provider to document medical necessity clearly. For more on navigating appeals, the patient advocacy resources on NewHealthInsurance.com can help you understand the steps.
When a Higher-Premium Plan Saves Money
The counterintuitive truth about health insurance for chronic conditions is that the cheapest premium is often the most expensive plan. Higher-premium plans, such as gold or platinum ACA plans, usually have lower deductibles, lower copays, and lower coinsurance. If you see specialists regularly, take multiple medications, or expect a procedure, the savings on cost-sharing can easily exceed the extra premium.
Consider a real-world example. A silver plan might have a $4,000 deductible and 40 percent coinsurance for specialty drugs, while a gold plan has a $1,000 deductible and 20 percent coinsurance. If you fill a $3,000-per-month specialty drug, the silver plan could cost you thousands before the out-of-pocket maximum kicks in, while the gold plan covers more from the start. The gold plan's higher premium is offset within a few months.
The decision hinges on your expected utilization. If your condition is stable and your only costs are a generic drug and two specialist visits per year, a lower-premium bronze or silver plan may be fine. If you have frequent flares, ongoing infusions, or planned surgery, run the annual cost estimate for each plan and compare the totals. Also check the out-of-pocket maximum: a plan with a lower maximum limits your worst-case scenario, which matters when you cannot predict your care needs.
For small business owners and self-employed people with chronic conditions, the same logic applies to group and individual plans. NewHealthInsurance.com compares individual, family, and small business plans across all 50 states, so you can see how different metal tiers affect your total costs. If you are also thinking about long-term financial protection for your family, FindTermLife connects you with licensed agents who can help you compare term life insurance quotes that fit your goals.
Checklist for Choosing a Chronic-Care Plan
Before you enroll, work through a structured checklist so you do not miss a critical detail. The following steps will help you compare plans with confidence and avoid surprises after your coverage starts.
- List every medication you take, including dose and frequency, and check each plan's formulary for tier, restrictions, and specialty pharmacy requirements.
- Confirm that your specialists, primary care doctor, hospital, and labs are in the plan's network for the coming year.
- Estimate your annual costs by adding 12 months of premiums to expected copays, coinsurance, and deductible spending, then cap at the out-of-pocket maximum.
- Review prior authorization and referral rules for your regular treatments, and ask your provider's office how they handle paperwork.
- Check whether the plan covers out-of-network care and what you would pay if you need it.
After you complete the checklist, compare at least three plans side by side. Pay attention to the total annual cost, not just the premium, and read the summary of benefits and coverage for each plan. If you are unsure, call the plan or a broker and ask specific questions about your drugs and doctors. A licensed agent can confirm formulary details and network status that are not obvious from marketing materials.
Open Enrollment is the main window to change plans, but qualifying life events such as marriage, a move, or loss of other coverage can open a special enrollment period. If you miss Open Enrollment and do not qualify for a special period, short-term plans may bridge the gap, but they often exclude pre-existing conditions and do not cover chronic care the way ACA plans do. Be cautious about relying on short-term coverage if you have an ongoing condition.
Get Help Comparing Plans
Health insurance for chronic conditions finding the right plan takes a little homework, but the payoff is real: lower total costs, fewer interruptions in care, and peace of mind. Start with your medication list and your care team, then compare formularies, networks, and cost-sharing. If the math is close, choose the plan with the lower out-of-pocket maximum and the better prior authorization track record.
NewHealthInsurance.com is a licensed brokerage that works with major carriers such as Humana, Cigna, Anthem, Kaiser Permanente, Aetna, Coventry Health Care, and Ambetter Health. You can compare plans in minutes and get help from certified experts at (833) 864-8035. Whether you are navigating Open Enrollment, a qualifying life event, or simply want to confirm your doctors and drugs are covered, a quick conversation can save you from a costly mistake. Take the time to choose a plan that supports your health, not just your budget.
Compare health plans
Finding plans in your area…