EPO Health Insurance Plan Benefits and Network Rules Explained
EPO health insurance plan benefits and network rules explained: lower premiums, no referrals, but stay in-network. Call (833)-864-8035 for expert guidance.
By Colin Stratford
Compare health plans
Finding plans in your area…
Choosing a health insurance plan can feel like deciphering a secret code, especially when terms like EPO, HMO, PPO, and POS get tossed around. If you are looking for a balance between lower premiums and some flexibility, an Exclusive Provider Organization (EPO) plan might be on your radar. But what exactly are the benefits of an EPO, and how do the network rules work? Understanding these details is crucial to avoiding surprise bills and getting the care you need. This guide breaks down EPO health insurance plan benefits and network rules explained in plain language, so you can decide if an EPO fits your healthcare needs and budget.
What Is an EPO Plan and How Does It Work?
An Exclusive Provider Organization (EPO) is a type of managed care health insurance plan. When you enroll in an EPO, you generally must use doctors, hospitals, and other healthcare providers that are part of the plan's network, except in emergencies. Unlike a Health Maintenance Organization (HMO) plan, you typically do not need a referral from a primary care physician to see a specialist. However, like an HMO, the network is exclusive: if you go outside the network for non-emergency care, you will likely pay the full cost yourself.
EPO plans are often offered through the Affordable Care Act (ACA) Marketplace, as well as by employers. They aim to keep costs down by negotiating discounted rates with a specific group of providers. In exchange for staying in-network, you get lower premiums and predictable out-of-pocket costs. According to the plan's design, you may have a deductible, copayments, and coinsurance, but these costs are usually lower than what you would face with a PPO plan. The trade-off is that you have less freedom to choose any provider you want.
One key feature of EPO plans is that they often do not require you to designate a primary care provider (PCP), though some plans may encourage it. This gives you more flexibility to see any in-network specialist without a referral, which can be a significant advantage over HMOs. However, the network can be narrower than a PPO's, so it is essential to check that your preferred doctors and hospitals are included before enrolling. For a deeper dive into how billing works when you use your plan, including how hospitals process claims, you can refer to our guide on how billing works in health insurance USA hospitals.
Key Benefits of EPO Health Insurance Plans
EPO plans offer several advantages that make them attractive to many consumers, particularly those who are generally healthy and want to save on premiums. The most notable benefit is cost: EPOs tend to have lower premiums and lower out-of-pocket costs compared to PPO plans. Because the insurer has more control over the network, they can negotiate better rates and pass some of those savings on to you. Additionally, EPOs often have lower deductibles and copayments for in-network services, making them a budget-friendly option for routine care.
Another benefit is the simplicity of not needing referrals for specialists. With an HMO, you often need your PCP to refer you to a specialist, which can add steps and delays. With an EPO, you can directly book an appointment with an in-network specialist, which can be especially valuable if you have a condition that requires ongoing specialist care. This flexibility, combined with lower costs, makes EPOs a popular choice for individuals and families who are willing to stay within a defined network.
EPO plans also often provide comprehensive coverage for essential health benefits, including preventive care, prescription drugs, and mental health services, as required by the ACA for Marketplace plans. Many EPOs offer telehealth services and other convenient features. For small business owners and self-employed individuals, EPOs can be a cost-effective way to offer or obtain coverage without the higher premiums of a PPO. To explore a range of EPO and other plan options, you can compare quotes on InsuranceShopping, a resource that helps consumers find and compare policies.
Here are some of the main benefits of EPO plans in summary:
- Lower premiums and out-of-pocket costs compared to PPO plans.
- No referrals needed to see in-network specialists.
- Comprehensive coverage for essential health benefits, including preventive care.
- Simplified access to care within a defined network.
- Often available through ACA Marketplaces with subsidies for eligible individuals.
These benefits can translate into significant savings, especially if you do not need frequent care from out-of-network providers. However, it is important to weigh these advantages against the restrictions of the network, which we will cover next.
EPO Network Rules: What You Need to Know
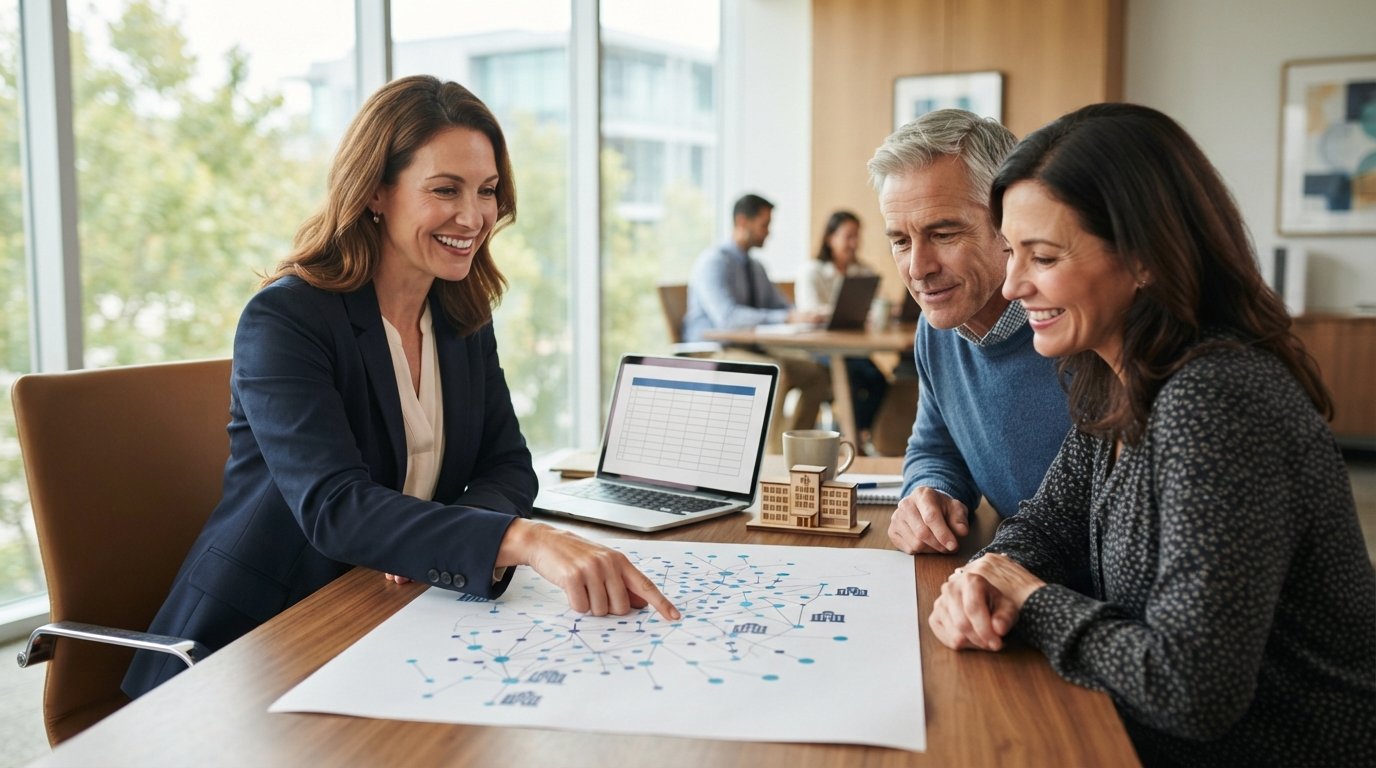
The defining feature of an EPO plan is its network rules. With an EPO, you must receive non-emergency care from providers within the plan's network. If you go outside the network, the plan generally will not pay for the service, except in specific situations such as emergencies. This is different from a PPO, which allows you to see out-of-network providers but at a higher cost. Understanding these rules is critical to avoiding unexpected medical bills.
Emergency care is a key exception. Under federal law, if you have an emergency medical condition, your EPO must cover emergency services at the in-network cost-sharing level, regardless of whether the hospital or provider is in your network. This includes emergency room visits and stabilization. However, follow-up care after the emergency may be subject to network rules, so you should always check with your plan. Additionally, some EPOs may have limited out-of-network coverage for certain services, but this is not guaranteed, so read your plan documents carefully.
Another important rule is that you typically do not need a referral to see a specialist, but you must ensure the specialist is in the network. If you see an out-of-network specialist, you will likely be responsible for the full bill. Some EPOs may require pre-authorization for certain services, such as surgeries or advanced imaging, so it is wise to check with your insurer before undergoing major procedures. For a broader overview of how different plans handle networks and billing, you can explore resources on NewHealthInsurance.com, which offers educational guides and comparison tools.
To stay within the network, always verify that your doctors, hospitals, labs, and other providers are listed in the plan's directory. Networks can change, so it is a good idea to recheck each year during open enrollment. If you have a preferred provider who is not in the network, you may need to switch plans or be prepared to pay out of pocket. Understanding these network rules is essential to making an EPO work for you.
How EPOs Compare to HMO, PPO, and POS Plans
To fully grasp EPO health insurance plan benefits and network rules explained, it helps to see how EPOs stack up against other common plan types. Each plan type has its own rules for networks, referrals, and out-of-network coverage, which affect your costs and flexibility.
HMO (Health Maintenance Organization): HMOs typically require you to stay in-network (except for emergencies) and often require a referral from a primary care physician to see a specialist. They usually have lower premiums and out-of-pocket costs but offer the least flexibility. EPOs are similar to HMOs in that they generally do not cover out-of-network care, but EPOs usually do not require referrals, giving you more freedom to see specialists.
PPO (Preferred Provider Organization): PPOs allow you to see any provider, but you pay less if you stay in-network. They do not require referrals and offer the most flexibility, but they come with higher premiums and higher out-of-pocket costs. EPOs are a middle ground: they offer lower costs than PPOs but restrict you to the network. If you value lower premiums and are willing to stay in-network, an EPO can be a good alternative to a PPO.
POS (Point of Service): POS plans combine features of HMOs and PPOs. You typically need a referral to see a specialist, and you can use out-of-network providers at a higher cost. POS plans may have lower premiums than PPOs but higher than HMOs. EPOs differ from POS plans in that EPOs generally do not cover out-of-network care (except emergencies) and do not require referrals.
The choice between these plans depends on your healthcare needs and budget. If you rarely see specialists and want to save money, an EPO or HMO might be suitable. If you need flexibility to see any provider, a PPO or POS may be better, despite the higher costs. For personalized guidance, you can call NewHealthInsurance.com at (833) 864-8035 to speak with a licensed agent who can help you compare plans.
When Do EPO Plans Make Sense Financially?
EPO plans are often a smart financial choice for individuals and families who are generally healthy and do not anticipate needing care from out-of-network providers. Because EPOs have lower premiums and lower out-of-pocket costs for in-network care, they can save you money on monthly premiums and when you need routine services. If you have a preferred doctor or hospital that is in the EPO network, you can benefit from the cost savings without sacrificing access to care.
EPOs can be particularly advantageous for people who need specialist care but do not want the hassle of referrals. Since EPOs typically do not require referrals, you can directly see an in-network specialist, which can save time and streamline your care. If you have a chronic condition that requires ongoing specialist visits, an EPO with a broad network may be a cost-effective option. However, you must ensure that your specialists are in the network, or you could face high out-of-pocket costs.
On the other hand, if you have a preferred provider who is not in the EPO network, or if you travel frequently and need access to providers across the country, a PPO might be a better fit despite the higher premiums. EPOs may also have narrower networks in some regions, so it is essential to check the provider directory. If you are considering an EPO, use the plan's online tools to search for your doctors and hospitals. You can also get quotes and compare EPO plans from multiple carriers on NewHealthInsurance.com to see which offers the best value for your needs.
What Happens If You Go Out of Network Under an EPO?
One of the most critical rules to understand is what happens if you go out of network under an EPO. In most cases, the plan will not pay for non-emergency services received from out-of-network providers. This means you could be responsible for the entire bill, which can be substantial. For example, if you see an out-of-network specialist for a routine visit, you may have to pay the full cost out of pocket, and that amount may not count toward your deductible or out-of-pocket maximum.
There are limited exceptions. As mentioned, emergency care is covered at in-network rates regardless of where you receive it. Additionally, some EPOs may cover out-of-network care if there is no in-network provider available for a specific service, but this is not standard and usually requires prior approval from the plan. You should always contact your insurer before seeking out-of-network care to understand your coverage and potential costs.
If you accidentally receive care from an out-of-network provider, you may be able to request a network exception or appeal the decision if you believe the service was necessary and no in-network provider was available. However, these processes can be time-consuming and are not guaranteed. The best strategy is to always verify network status before receiving care. Keep in mind that network directories can sometimes be outdated, so it is wise to confirm with the provider's office that they are still in the network and accepting your plan.
How to Check That Your Doctors and Hospital Are in an EPO Network
Before enrolling in an EPO plan, it is essential to verify that your preferred doctors, hospitals, and other providers are in the network. Here is a step-by-step approach to checking network participation:
- Visit the insurance carrier's website and use their provider directory search tool. Enter your location and the plan name to see a list of in-network providers.
- Call your doctors' offices directly and ask if they are in the specific EPO network. Provide the plan name and network name, as insurers may have multiple networks.
- Check with the hospital you prefer to use. Ask if they are in-network for the EPO plan and if your doctors have privileges there.
- If you have ongoing prescriptions, verify that your pharmacy is in the network and that your medications are on the plan's formulary.
- Document your findings and recheck annually, as networks can change.
Taking these steps can save you from surprise bills and ensure continuity of care. If you find that your key providers are not in the network, you may want to consider a different plan or be prepared to pay out of pocket. NewHealthInsurance.com offers tools to compare plans and check network participation, and their licensed agents can assist you in finding a plan that includes your providers. You can reach them at (833) 864-8035 for personalized help.
Understanding EPO health insurance plan benefits and network rules explained is the first step toward making an informed decision. By weighing the lower costs against the network restrictions, you can determine if an EPO aligns with your healthcare needs and financial goals. Whether you choose an EPO or another plan type, always review the details and confirm network participation to avoid unexpected expenses. With the right information and support, you can find a plan that provides peace of mind and access to quality care.
Compare health plans
Finding plans in your area…